Should I Switch Financial Advisors? 7 Warning Signs It's Time to Move Your Wealth
Changing financial advisors can be a significant decision, particularly when your investments, retirement plans, taxes, and other financial priorities are connected. But staying with an advisor simply because you have worked together for years is not always the right choice.
Your financial situation may have changed. Your advisor's firm may have been acquired. Investment costs may be higher than you realized, or your portfolio may no longer reflect your goals and risk tolerance. In some cases, the relationship itself may no longer provide the level of planning, communication, or expertise you need.
Here are seven warning signs that it may be time to reconsider your financial advisor, along with practical steps to evaluate your options.
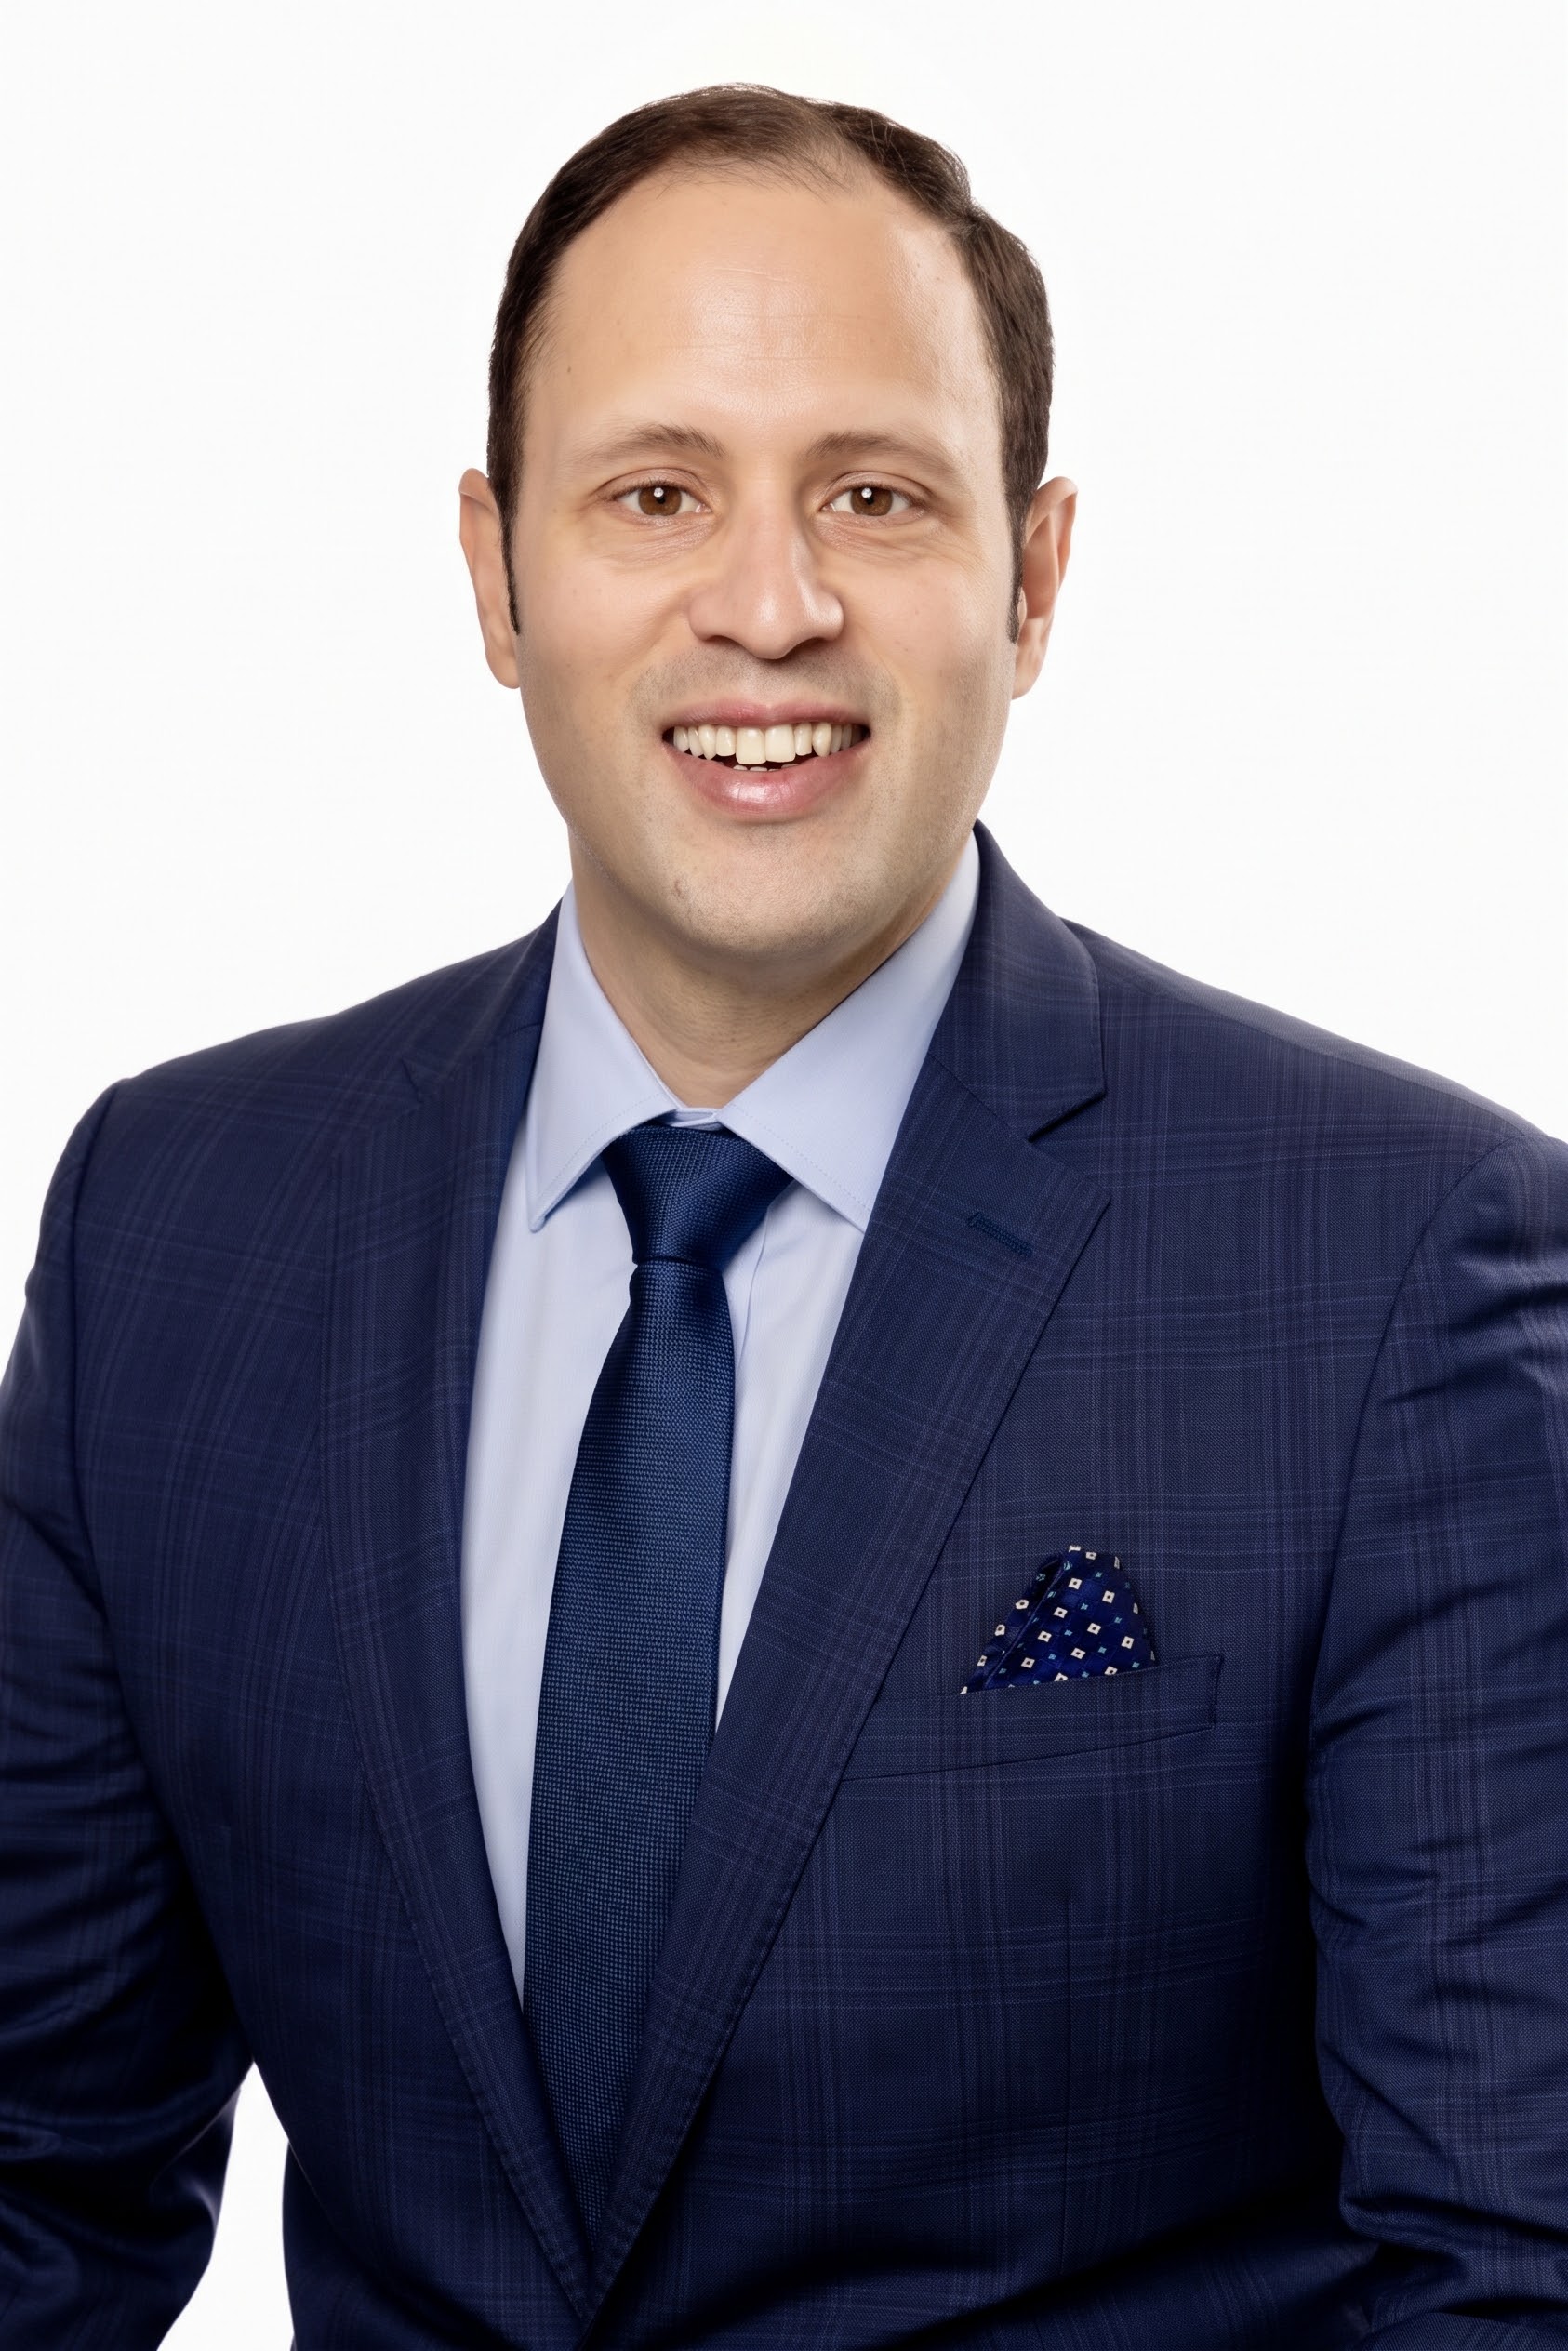
Founder, Inclinevest Wealth Management
Consider changing financial advisors if you no longer receive appropriate financial planning, your investments are unnecessarily expensive or risky, your advisor has conflicting incentives, communication has deteriorated, or a change in firm ownership could materially affect your relationship. Before making a move, compare the services, costs, investment approach, and long-term direction of the firms you are considering.
Switching advisors is not necessarily about finding someone who predicts markets better or promises higher returns. It is about finding an advisory relationship that fits your financial circumstances, provides appropriate oversight, and can support your needs as they evolve.
1. Your Financial Advisory Firm Is Being Sold or Has No Clear Succession Plan
A change in ownership can have a significant impact on a financial advisory relationship. Your advisor may have been the primary reason you chose the firm, but that does not necessarily mean the same person, service model, or investment philosophy will remain after an acquisition.
Many independent advisory firms eventually face succession decisions. Some are acquired by larger wealth management organizations or private equity-backed platforms. Others merge with competing firms or transition clients to a new generation of advisors.
An acquisition is not automatically a problem. A larger organization may offer additional resources, technology, or specialized services. However, the transaction can also change how the firm operates, how advisors are compensated, how many clients each advisor serves, and how much direct access clients receive.
Questions to ask when your advisory firm changes ownership
- Will your current advisor continue managing your relationship?
- Will the firm's investment philosophy or planning process change?
- Will your fees increase or will new products and services be introduced?
- Will your advisor have more clients or additional sales responsibilities?
- Who will oversee your financial plan if your advisor retires or leaves?
- Does the firm have a clear succession plan that protects client relationships?
Private equity ownership deserves particular attention. An investment firm acquiring an advisory business may have objectives that extend beyond providing financial advice. Growth targets, operating efficiencies, acquisitions, and eventual resale considerations can influence how the business is managed.
That does not mean every private equity-backed advisory firm provides poor service. It does mean clients should understand who owns their advisory firm, what the new ownership structure means, and whether the firm's priorities remain aligned with their expectations.
Inclinevest Wealth Management has no plans to sell the firm to private equity or pursue growth into a large wealth management organization. The intention is to remain independent and maintain a manageable client base, preserving direct relationships and personal involvement in the financial advice provided.
For clients who value continuity and direct access to the people responsible for their financial planning, the ownership and long-term direction of an advisory firm should be part of the selection process.
2. Your Financial Advisor Is Not Acting as a Fiduciary
Not every financial professional operates under the same legal standard or compensation structure. Some advisors are compensated through commissions, product sales, referral arrangements, or other incentives that can create conflicts between their financial interests and yours.
A fiduciary financial advisor is required to act in the client's best interest when providing fiduciary advice. That includes addressing conflicts of interest and providing appropriate disclosures.
Ask how your advisor is compensated and whether the firm receives commissions, revenue sharing, referral payments, or other compensation from investment or insurance providers.
Questions to ask about advisor compensation
- Does the advisor receive commissions for selling investments or insurance?
- Does the firm receive compensation from investment companies?
- Are there financial incentives to recommend certain products?
- Is the advisor acting as a fiduciary for the services being provided?
- Can you clearly understand the total cost of the advisory relationship?
Compensation alone does not tell you whether an advisor is providing good advice. However, understanding how an advisor is paid can help you identify potential conflicts and evaluate whether the relationship is structured around your interests.
The firm provides financial planning and investment advisory services to clients nationwide. Inclinevest does not earn commissions from selling investment or insurance products.
For households with $5 million or more in assets under management, the annual advisory fee is 0.50%. Flat-fee arrangements may apply where appropriate. The scope of services and applicable fee depend on the client's financial situation, assets, planning needs, and the services involved.
3. Your Investments Are More Expensive Than You Realize
Investment costs can have a meaningful effect on long-term portfolio results. Yet many investors do not know what they are paying across their investment accounts.
Your advisory fee is only one part of the total cost. Mutual fund and ETF expense ratios, transaction costs, underlying investment expenses, and certain account or product charges can add to the overall cost of managing your wealth.
Some portfolios include expensive actively managed funds, proprietary investment products, structured investments, or multiple layers of fees. These costs should be evaluated in relation to the services, investment strategy, and potential benefits being provided.
Look beyond the advisory fee
When reviewing your current relationship, request a breakdown of:
- Your financial advisor's annual advisory fee.
- Expense ratios for mutual funds and ETFs.
- Any underlying product or investment management fees.
- Transaction, account, or platform charges.
- Additional costs associated with specialized investment products.
A lower advisory fee does not automatically mean a better relationship. The relevant comparison is the total cost of the investment and planning services you receive, along with the quality and suitability of the advice.
At Inclinevest, investment costs are part of the portfolio evaluation process. The firm uses an open-architecture investment approach, primarily utilizing low-cost mutual funds and ETFs from established providers such as Vanguard and iShares. Investment selections are evaluated based on their costs, diversification, underlying holdings, tax considerations, and role within the overall financial plan.
4. Your Portfolio Is Overly Complicated, Risky, or Poorly Diversified
A complicated investment strategy can create the impression that your portfolio is sophisticated. But complexity does not necessarily improve diversification, reduce risk, or increase the likelihood of achieving your financial objectives.
Some portfolios contain numerous overlapping funds, concentrated positions, speculative investments, complex structured products, or strategies that are difficult to explain. Others may take substantial risks without a clear connection to the investor's financial plan.
The issue is not whether a portfolio contains a large number of investments. It is whether those investments work together in a coherent way.
Warning signs of an unnecessarily complicated portfolio
- You cannot explain what each major investment is intended to accomplish.
- Several funds hold substantially the same stocks or bonds.
- Your portfolio has concentrated exposure to a small number of companies, sectors, or investment themes.
- You hold illiquid or complex products without understanding their risks.
- Your portfolio takes more risk than your financial plan requires.
- Your advisor frequently recommends new strategies without explaining how they fit together.
A sound investment strategy should reflect your time horizon, income needs, tax situation, risk tolerance, and broader financial objectives. It should also be understandable enough that you can explain why the major components are in your portfolio.
Diversification does not eliminate investment risk or guarantee a positive return. It can, however, help reduce the impact of excessive exposure to individual securities, industries, or asset classes.
If we removed this investment from the portfolio, what specific role would be missing, and why is this investment a better fit than a simpler alternative?
5. Your Advisor Does Not Understand Your Full Financial Situation
Investment management is only one part of financial planning. As your wealth grows, financial decisions become increasingly interconnected.
Your advisor should understand more than the balance of your investment accounts. They should have a working understanding of your income, retirement plans, tax exposure, business interests, real estate, charitable intentions, estate planning considerations, and family priorities.
This becomes particularly important for executives, business owners, and households with multiple sources of wealth. Equity compensation, deferred compensation, concentrated stock positions, business ownership, retirement accounts, and taxable investments can create financial decisions that should not be evaluated in isolation.
Signs your advisor may not understand the bigger picture
- Recommendations are made without considering your tax situation.
- Your advisor rarely asks about changes in income, employment, or family circumstances.
- Retirement projections are not updated as your circumstances change.
- Equity compensation or concentrated stock positions are not incorporated into your plan.
- Investment decisions are made without considering estate or charitable planning.
- You repeatedly have to explain the same financial details to different people at the firm.
A financial plan should connect the major parts of your financial life. It should help you understand how decisions in one area may affect another, rather than treating each account or financial goal as a separate project.
6. Your Investment Management and Financial Planning Are Disconnected
Some advisory relationships focus almost entirely on investment performance. You may receive portfolio reports and occasional market commentary, but little ongoing guidance about retirement, taxes, spending, or other financial decisions.
Other firms provide a financial plan at the beginning of the relationship but rarely revisit it. The plan becomes a document rather than an active part of the advice you receive.
Investment management and financial planning should inform each other. Your portfolio should support your financial plan, and your financial plan should be updated as your investments, income, goals, and circumstances change.
What an integrated advisory relationship should address
- Retirement income projections and withdrawal strategies.
- Tax-aware investment management and account location.
- Social Security and retirement benefit decisions.
- Equity compensation and concentrated stock considerations.
- Charitable giving and donor-advised fund strategies.
- Estate planning coordination and wealth transfer considerations.
- Changes in spending, savings, income, and long-term goals.
The appropriate level of planning depends on your circumstances. A household approaching retirement may need detailed income projections, while an executive with substantial equity compensation may need help coordinating vesting schedules, diversification, and tax planning.
The important question is whether the advice you receive connects your investments to the decisions that affect your financial future.
7. The Service No Longer Matches Your Needs
Your financial needs can change considerably over time. An advisor who was a good fit when you first started investing may not provide the expertise, communication, or planning support you need today.
Perhaps your assets have grown, you have changed careers, you are approaching retirement, or your financial life has become more complicated. You may need more coordination and proactive advice than your current relationship provides.
Service issues can also become more noticeable when an advisory firm grows. Your original advisor may have delegated much of the relationship to a service team, or you may find it increasingly difficult to schedule a meeting or receive a clear answer.
Questions to consider
- Can you reach your advisor when an important financial decision arises?
- Does your advisor proactively contact you when planning issues need attention?
- Are meetings focused on your financial priorities rather than generic market updates?
- Does the firm have the expertise to address your current financial circumstances?
- Do you know who is responsible for your relationship and financial plan?
- Are you receiving the level of service you expected when you hired the firm?
A good advisory relationship should provide a clear point of contact, appropriate communication, and advice that reflects your current circumstances. You should not have to repeatedly chase your advisor for answers to important questions.
How to Evaluate a New Financial Advisor Before Switching
If one or more of these warning signs apply, take time to evaluate alternatives before making a decision. A new advisor should be able to explain how the relationship will work, what services are included, how compensation is structured, and how your investments and financial plan will be managed.
- Understand the firm's compensation. Ask whether the advisor is fee-only, whether commissions or referral payments are involved, and how the total cost of the relationship is calculated.
- Ask who will actually manage your relationship. Understand who prepares your plan, makes investment recommendations, conducts meetings, and responds to questions.
- Review the investment philosophy. Ask how the firm approaches diversification, investment costs, taxes, risk management, and portfolio rebalancing.
- Understand the financial planning process. Find out how often your plan is updated and how investment decisions connect with retirement, taxes, and other financial priorities.
- Review the firm's ownership and succession plans. Ask who owns the firm, whether outside investors are involved, and what happens if your primary advisor retires or leaves.
- Compare the actual services and fees. Do not compare advisory fees alone. Consider the planning, investment management, communication, and ongoing support included in each relationship.
How Do You Switch Financial Advisors?
Moving to a new financial advisor is generally more straightforward than many investors expect. You do not necessarily need to liquidate your investments or move every account at once.
The process typically begins with an introductory conversation and a review of your current financial situation. Once you decide to move forward, the new advisory firm can help coordinate the account transfer process.
Typical steps when changing financial advisors
- Review your current advisory agreement. Understand termination requirements, notice provisions, outstanding fees, and any account-specific restrictions.
- Evaluate the new advisory relationship. Review the firm's services, investment philosophy, compensation, and planning process before signing an agreement.
- Review your existing investments. Identify any investments that may have transfer restrictions, surrender charges, tax consequences, or other limitations.
- Coordinate account transfers. Many brokerage accounts can transfer in kind, meaning eligible investments move without being sold. Some investments may need to be liquidated or handled separately.
- Establish the new financial planning relationship. Provide account statements and relevant financial information so your new advisor can evaluate your complete situation.
Be careful about selling investments simply to make a transfer easier. Liquidating appreciated securities in a taxable account can create capital gains, and certain investments may have restrictions or other costs. A transfer should be evaluated based on the specific holdings and account type.
Considering a Change in Financial Advisors?
If you are evaluating a new financial advisory relationship, an introductory conversation can help you understand how a different approach to financial planning and investment management may fit your circumstances.
Inclinevest Wealth Management works with professionals, executives, business owners, and retirees who want coordinated financial planning and investment management through an independent, fee-only fiduciary firm.
Schedule an Introductory ConversationWhy Consider Inclinevest Wealth Management?
Inclinevest Wealth Management is an independent, fee-only fiduciary financial advisory firm based in Colorado and serving clients nationwide. The firm works with professionals, executives, business owners, and retirees who want financial planning and investment management coordinated around their broader financial circumstances.
The firm was founded by Gabriel Motta, CFP®, MBA, AWMA™, who has more than 20 years of experience in financial services. His background includes wealth planning and advisory roles at GE Capital, UBS, U.S. Bank, and BBVA, now part of PNC.
Inclinevest emphasizes direct advisor relationships, financial planning, investment cost awareness, and diversified portfolio management. The firm uses Charles Schwab as its independent custodian and RightCapital for financial planning.
Inclinevest has no plans to sell the firm to private equity or pursue growth into a large wealth management organization. The intention is to maintain an independent practice with a manageable client base and direct involvement in client relationships.
Advisory fees depend on the assets managed, planning needs, and scope of services. For households with $5 million or more in assets under management, the annual advisory fee is 0.50%. Flat-fee arrangements may apply where appropriate.
Learn more about Inclinevest Wealth Management, its financial planning and wealth management services, and the firm's advisory fees.
Talk With an Independent Financial Advisor
If you are considering changing financial advisors, schedule an introductory conversation to discuss your current advisory relationship, financial priorities, and what you are looking for in a new firm.
Schedule an Introductory ConversationFrequently Asked Questions About Switching Financial Advisors
When should I switch financial advisors?
Consider switching when your advisor no longer provides the planning, investment management, communication, or expertise you need. Other reasons may include excessive investment costs, conflicts of interest, an unsuitable portfolio, or a change in firm ownership that affects your relationship.
Is it difficult to switch financial advisors?
In many cases, switching is relatively straightforward. A new advisory firm can often help coordinate the transfer of eligible investment accounts. Some assets may transfer in kind, while others may require additional review because of restrictions, tax considerations, or account-specific requirements.
Will I have to sell my investments when I change advisors?
Not necessarily. Many publicly traded stocks, bonds, mutual funds, and ETFs can transfer between custodians without being sold. However, proprietary investments, certain mutual funds, annuities, and other restricted holdings may require additional steps. Review potential tax consequences before liquidating investments in taxable accounts.
How do I know whether my financial advisor is a fiduciary?
Ask your advisor directly whether they act as a fiduciary when providing investment advice. Review the firm's Form ADV and advisory agreement for information about services, compensation, conflicts of interest, and other disclosures. You can also review the firm's registration and disclosure information through the SEC's Investment Adviser Public Disclosure database.
Should I switch financial advisors if my firm is acquired?
An acquisition does not automatically mean you should leave. First, understand how ownership changes may affect your advisor, fees, investment philosophy, service model, and succession arrangements. If the new direction no longer matches your expectations, comparing independent alternatives may make sense.
Are fee-only financial advisors better?
Fee-only advisors are compensated directly by clients rather than through commissions from selling investment or insurance products. This can reduce certain product-related conflicts, but it does not guarantee that every recommendation is appropriate or that every fee-only advisor is the right fit. Evaluate the firm's services, investment approach, compensation, and fiduciary obligations.
Can I change financial advisors if I have more than $1 million invested?
Yes. Investors with substantial assets may have additional considerations involving taxes, concentrated stock positions, retirement accounts, trusts, charitable giving, and estate planning. A new advisor should understand these issues before recommending changes to your investments or accounts.
Does Inclinevest Wealth Management work with clients outside Colorado?
Yes. Inclinevest Wealth Management is based in Colorado and serves clients nationwide, providing financial planning and investment management remotely.
What does Inclinevest Wealth Management charge?
Fees depend on the assets managed, financial planning needs, and scope of services. For households with $5 million or more in assets under management, the annual advisory fee is 0.50%. Flat-fee arrangements may apply where appropriate. The applicable fee is discussed before entering into an advisory relationship.
The Bottom Line: Your Financial Advisor Should Fit Your Financial Life Today
The decision to change financial advisors should be based on more than short-term investment performance or a disappointing market year. Consider whether your current advisor understands your financial circumstances, provides appropriate planning, manages investments in a disciplined manner, communicates effectively, and operates under a compensation structure you understand.
Your financial needs will likely evolve over time. The advisory relationship should be able to evolve with them. If your current firm no longer provides the level of service, expertise, or alignment you expect, it may be time to consider other options.
If you are evaluating a change, an introductory conversation with Inclinevest Wealth Management can help you understand whether an independent, fee-only fiduciary approach is appropriate for your situation.
Schedule an introductory conversation with Inclinevest Wealth Management.