Colorado Capital Gains Tax on Stock Sales and Business Exits: What Investors Need to Know
Selling appreciated stock, exercising company equity or selling a privately held business can create a substantial tax liability. For Colorado investors, the amount retained after a major financial transaction depends on more than the sale price. Federal taxes, Colorado income taxes, transaction structure, residency and the timing of the gain all matter.
Yes. Colorado generally includes taxable capital gains in its state income tax calculation. There is no broad Colorado capital gains exemption for selling publicly traded stocks, ETFs or most private-company shares.
Colorado's individual income tax rate is 4.4% for 2026. Voters approved Amendment 87 in November 2026, replacing the flat rate with graduated marginal rates beginning in tax year 2027. The new rates range from 3.7% to 8.4%, depending on taxable income.
For investors planning a large stock sale or business exit, the change makes the timing and amount of recognized income especially important.
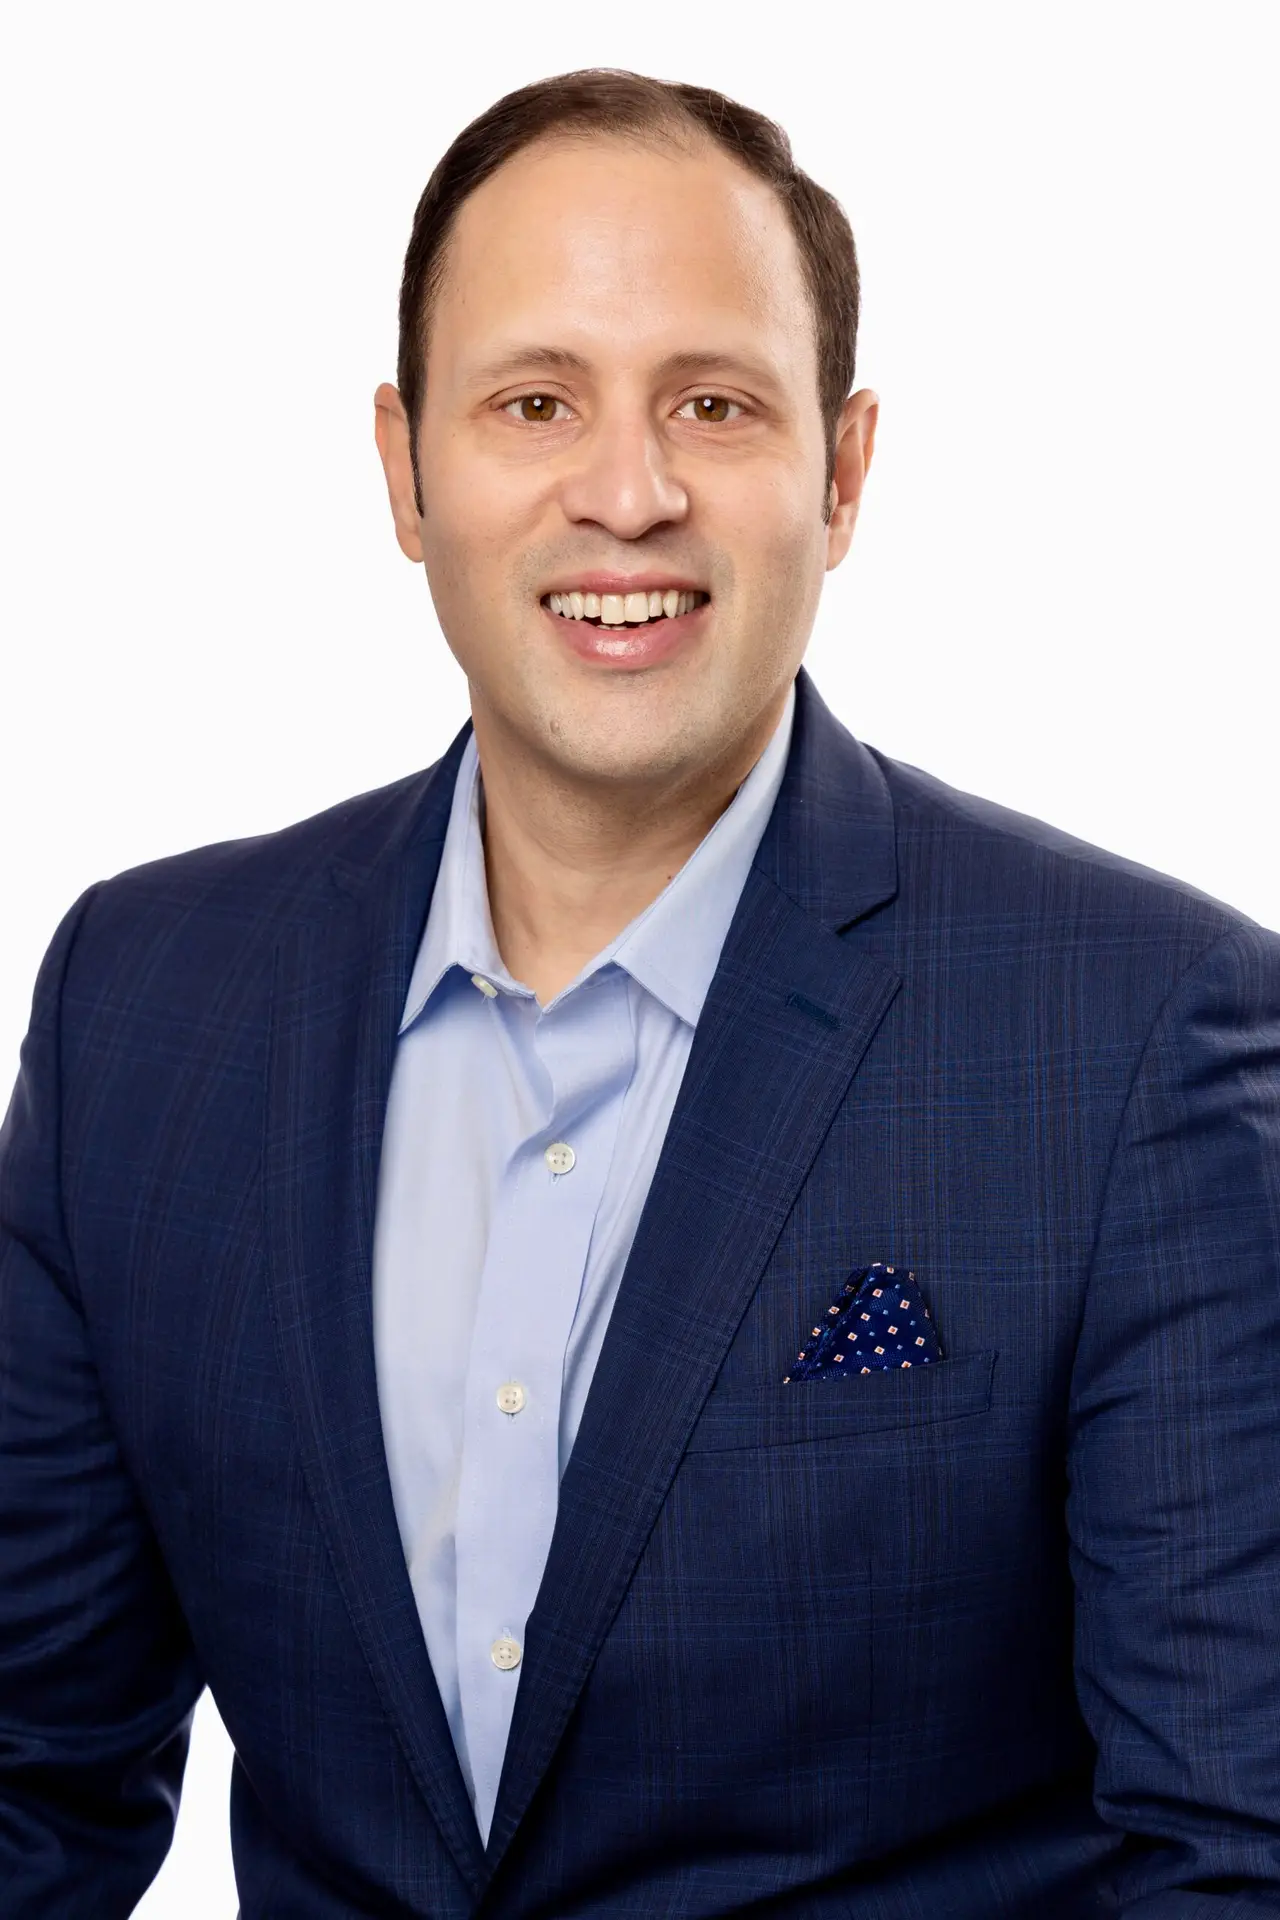
More than 20 years in financial services, helping professionals, executives, business owners and retirees navigate investment decisions, retirement planning and significant financial transitions.
Meet your advisorAt Inclinevest Wealth Management, I work with households navigating concentrated stock positions, equity compensation, business liquidity events and the investment decisions that follow a major financial transaction.
Tax planning is one part of the process. The broader questions include how much of the proceeds to invest, how to diversify, how to generate retirement income and how to coordinate investment decisions with a CPA and estate-planning attorney.
Planning before a liquidity event can help you evaluate the tax consequences, investment strategy and financial decisions that follow.
Schedule an introductory consultation →Does Colorado Have a Separate Capital Gains Tax?
Colorado does not generally impose a separate capital gains tax with its own preferential rate structure. Instead, capital gains included in federal taxable income generally flow into the Colorado income tax calculation, subject to applicable state additions and subtractions.
This means the state generally taxes gains from publicly traded stock, mutual funds, ETFs, privately held company shares and other investments when those gains are included in the Colorado tax base.
Federal tax law distinguishes between short-term and long-term capital gains. Qualifying long-term gains generally receive preferential federal tax rates. Colorado does not provide a corresponding general reduced rate for long-term investment gains.
For example, an investor who sells shares held for five years may qualify for the federal long-term capital gains rate. The taxable gain is still generally included in Colorado taxable income.
What are Colorado's capital gains tax rates in 2026 and 2027?
Colorado's individual income tax rate is 4.4% for tax year 2026. Following voter approval of Amendment 87, a graduated marginal rate structure takes effect for tax year 2027.
| Colorado taxable income | 2026 rate | 2027 marginal rate |
|---|---|---|
| First $25,000 | 4.40% | 3.70% |
| $25,001–$100,000 | 4.40% | 4.20% |
| $100,001–$500,000 | 4.40% | 4.40% |
| $500,001–$750,000 | 4.40% | 7.40% |
| $750,001–$1,000,000 | 4.40% | 7.90% |
| Above $1,000,000 | 4.40% | 8.40% |
These are marginal rates, not flat rates applied to all income. A taxpayer with $1 million of Colorado taxable income does not pay 8.4% on the entire amount. Each portion of taxable income is subject to the rate assigned to its bracket.
The rate schedule applies to taxable income under the measure's rules. The actual tax calculation may differ from a simple multiplication of a capital gain by one of these rates.
Amendment 87 also maintains the existing 4.4% rate for income from the sale of a principal residence, as specified in the measure. That treatment should not be confused with the federal exclusion for qualifying home-sale gains.
For investors considering a large stock sale, business exit or equity-compensation event in 2027, the new structure makes income projections particularly important.
How Much Tax Will You Pay When Selling Stock in Colorado?
The amount of Colorado tax on a stock sale depends on the taxable gain and the taxpayer's overall income, not simply the sale proceeds.
Generally, a capital gain is calculated by subtracting the adjusted cost basis and eligible selling expenses from the amount realized.
| Sale proceeds | $1,000,000 |
| Adjusted cost basis | $300,000 |
| Realized capital gain | $700,000 |
| Illustrative Colorado tax at 4.4% | $30,800 |
The $30,800 represents a simplified calculation of the Colorado tax attributable to the $700,000 gain at a 4.4% rate. It assumes the entire gain is included in Colorado taxable income and excludes other income, deductions, credits and adjustments.
If the same gain is recognized in 2027, the graduated brackets may produce a different state tax liability. The result depends on the taxpayer's total Colorado taxable income and the applicable tax rules.
Federal capital gains rates, the net investment income tax, capital losses, deductions and other income also affect the overall tax bill.
This is why investors should evaluate the after-tax proceeds of a transaction rather than relying on the gross sale price.
How Does Colorado Tax Private Company Stock and Equity Compensation?
Employees and executives at privately held technology, aerospace and defense companies may accumulate substantial equity over several years. A tender offer, secondary share sale, acquisition or public offering can create a significant taxable event.
The tax treatment depends on the type of equity, how it was acquired, the transaction structure and the taxpayer's circumstances.
Restricted stock units (RSUs)
RSUs generally become taxable compensation when they vest. The fair market value at vesting is typically included in W-2 wages and becomes the starting tax basis for the shares.
If the employee later sells the shares, the difference between the sale price and adjusted basis generally creates a capital gain or loss.
| RSU example | Amount |
|---|---|
| Value included in compensation at vesting | $200,000 |
| Subsequent sale proceeds | $260,000 |
| Additional capital gain | $60,000 |
The original $200,000 is generally not taxed again as a capital gain. The additional $60,000 is generally subject to the applicable capital gains rules.
Employees should verify that their brokerage cost basis reflects the compensation already reported on their W-2. Incorrect basis reporting can result in paying tax twice on the same economic income.
Incentive stock options (ISOs)
Incentive stock options have different tax rules from RSUs and nonqualified stock options.
Exercising an ISO generally does not create regular federal taxable compensation income, but the difference between the exercise price and fair market value may create an alternative minimum tax adjustment.
The eventual sale of the shares can qualify for long-term capital gains treatment if the applicable holding-period requirements are satisfied. A sale before satisfying those requirements may create a disqualifying disposition with some income treated as ordinary compensation.
Employees considering an ISO exercise should evaluate federal alternative minimum tax, Colorado income tax, exercise costs, company liquidity and concentration risk before proceeding.
Nonqualified stock options (NSOs)
Nonqualified stock options generally create ordinary compensation income when exercised. The difference between the fair market value of the shares and the exercise price is generally included in compensation income.
Any subsequent appreciation or decline is generally treated as a capital gain or loss when the shares are sold.
Because the compensation component and subsequent investment gain can receive different tax treatment, accurate cost-basis records are essential.
Private-company tender offers and secondary sales
Some private companies allow employees and early investors to sell a portion of their shares through tender offers or secondary transactions.
These opportunities can provide liquidity before an acquisition or public offering, but the tax consequences depend on the underlying equity and transaction terms.
Before participating, investors should review:
- Whether the shares are restricted stock, exercised options or another form of equity.
- The adjusted cost basis and any compensation previously recognized.
- Whether the transaction creates ordinary income, capital gain or both.
- Applicable holding periods and potential Section 1202 qualified small business stock eligibility.
- Company transfer restrictions and transaction limitations.
- Expected federal and Colorado tax liabilities.
- How much remaining company equity will continue to represent concentrated investment risk.
For employees at high-growth technology, aerospace and defense companies, a tender offer may be the first opportunity to diversify a substantial portion of their net worth.
The decision should account for taxes, future liquidity, company prospects and the role the remaining equity plays in the household's financial plan.
Inclinevest works with executives and professionals navigating RSUs, stock options, concentrated investments and the financial decisions surrounding company liquidity events.
Explore equity compensation planning →Schedule an introductory consultation →
What Happens When You Sell a Privately Held Business in Colorado?
Selling a business can create one of the largest taxable events in an owner's financial life. However, the tax treatment is not necessarily the same for every transaction.
The amount of tax depends on the entity structure, assets being transferred, purchase agreement, allocation of proceeds, cost basis and whether the transaction is structured as an asset sale or stock sale.
Asset sale versus stock sale
In an asset sale, the buyer purchases some or all of the business's underlying assets. Each asset is generally analyzed separately for federal tax purposes.
Different portions of the purchase price may be allocated to inventory, equipment, real estate, goodwill, intellectual property and other assets. The tax treatment can vary significantly.
In a stock sale, the buyer purchases ownership shares in the corporation. The seller generally recognizes gain based on the difference between the amount received and adjusted basis in the shares, subject to applicable exceptions.
| Consideration | Asset sale | Stock sale |
|---|---|---|
| What is transferred? | Selected business assets or substantially all assets | Ownership shares in the company |
| Tax treatment | Depends on the character of each asset | Generally capital gain or loss, subject to exceptions |
| Ordinary income exposure | May arise from inventory, depreciation recapture and other items | Can arise in certain circumstances |
| Purchase price allocation | Generally required under applicable federal rules | Different rules generally apply |
| Planning considerations | Asset allocation, basis and depreciation recapture | Share basis, holding period and exclusions |
An asset sale can produce a combination of ordinary income, capital gains and Section 1231 gains. A stock sale may produce predominantly capital gains, but the actual outcome depends on the company and transaction.
For S corporations, partnerships and LLCs taxed as partnerships, additional considerations apply. The character of income flowing through the entity and the specific assets being sold can affect the owner's individual tax liability.
Colorado tax treatment should be reviewed alongside the federal transaction analysis. A business sale should not be evaluated solely by comparing the purchase price with the owner's original investment.
Does Colorado Have a Capital Gains Tax Break for Selling a Business?
Colorado's capital gain subtraction is much narrower than many investors and business owners assume.
Colorado provides a subtraction for certain capital gains from qualifying agricultural real property for eligible taxpayers, subject to specific ownership, acquisition, holding-period and property requirements.
This is not a general exemption for selling an operating business, company shares, publicly traded stock or investment real estate.
Section 1202 qualified small business stock
Section 1202 of the Internal Revenue Code can allow eligible shareholders to exclude some or all qualifying federal capital gains from the sale of qualified small business stock.
The rules depend on several factors, including:
- The company's corporate structure and eligibility.
- The date the shares were originally issued.
- The company's gross asset limitations and qualifying business activities.
- The shareholder's acquisition method.
- The applicable holding period.
- Per-issuer exclusion limitations and other statutory requirements.
Federal legislation enacted in 2025 changed certain Section 1202 requirements for qualifying stock issued after July 4, 2025. These changes include revised holding-period, exclusion and company-asset provisions. Older and newer shares may be subject to different rules.
Federal Section 1202 eligibility should not be assumed to produce identical Colorado treatment. The interaction between the federal exclusion, Colorado's tax base and applicable state additions or subtractions should be reviewed with a CPA or tax attorney before a transaction.
For founders and early investors, reviewing potential Section 1202 eligibility well before an acquisition or liquidity event can be important.
Can Moving Out of Colorado Before Selling Stock Reduce State Taxes?
Some investors consider relocating to a state without an individual income tax before selling a large investment or business interest.
Moving may change future state income tax exposure, but it does not automatically eliminate Colorado tax obligations.
Colorado generally considers someone a resident if the individual is domiciled in Colorado or maintains a permanent place of abode in the state and spends more than six months of the tax year there.
Colorado residents are generally subject to state income tax on income from all sources. Nonresidents may still owe Colorado tax on income derived from Colorado sources.
What if you sell stock after moving?
The answer depends on the nature of the investment and how the income is sourced.
For ordinary investment securities held outside a Colorado business, a genuine change of residency before a taxable sale may affect which state has the right to tax the resulting gain.
However, Colorado-source income can remain taxable to a nonresident. Stock and partnership interests connected with a business, trade, profession or occupation carried on in Colorado may require separate sourcing analysis.
Colorado real estate generally remains Colorado-source income even after the owner relocates.
Partnership and other pass-through interests require additional analysis because the source of the gain can depend on the underlying business activity, the assets involved and applicable state sourcing rules.
Employees with equity compensation should also understand that moving before a stock vesting date or option exercise does not necessarily eliminate Colorado tax on compensation attributable to services performed in Colorado.
Changing your mailing address or spending part of the year outside Colorado does not automatically establish a new tax domicile. A relocation should be supported by actual changes in your residence, personal circumstances and connections to the state.
Before completing a relocation tied to a major stock sale or business exit, coordinate the timing, domicile analysis, transaction documents and income-sourcing treatment with a qualified tax professional.
How Can You Reduce Capital Gains Taxes Before Selling Stock or a Business?
There is no single strategy that works for every investor. The most effective approach depends on the asset, size of the gain, expected transaction date, taxpayer's other income and future financial needs.
1. Plan the timing of the sale
The year in which a gain is recognized can affect both federal and Colorado income taxes.
For a Colorado investor considering a large sale in 2026 or 2027, the new graduated state tax structure makes income timing particularly important.
A sale in 2026 may be subject to the existing 4.4% Colorado rate, while a sale in 2027 may be subject to graduated marginal rates reaching 8.4% for taxable income above $1 million.
However, accelerating a sale is not automatically beneficial. Federal capital gains rates, the net investment income tax, transaction pricing, business conditions, contractual restrictions and investment risk must also be considered.
2. Evaluate charitable giving before selling appreciated stock
Donating appreciated publicly traded securities directly to a qualifying charitable organization or donor-advised fund may provide two potential benefits for eligible taxpayers.
- The donor may avoid recognizing capital gains on the donated shares.
- The donor may qualify for a federal charitable income tax deduction, subject to applicable limitations.
This can be particularly useful for executives and business owners who have accumulated highly appreciated investment positions and already intend to make significant charitable contributions.
Timing is essential. A contribution generally needs to occur before a binding sale or assignment of the gain. Donating shares after a sale has become legally committed may not avoid the capital gain.
Private-company shares require additional review because transfer restrictions, valuation requirements, the charitable recipient's acceptance policies and potential prearranged-sale issues can complicate the transaction.
3. Diversify concentrated stock positions over time
Investors who have accumulated substantial employer stock or a single appreciated position often face a difficult decision: continue holding the investment or sell shares and recognize a large taxable gain.
A concentrated position can expose a household to substantial company-specific risk, particularly when employment income, equity compensation and investment assets are tied to the same company.
A diversification strategy should consider:
- Existing unrealized gains and tax basis.
- Annual income and projected tax brackets.
- RSU vesting schedules and option expiration dates.
- Potential charitable contributions.
- Tax-loss harvesting opportunities.
- Portfolio allocation and retirement income requirements.
For executives and employees at private technology and aerospace companies, this planning can be particularly important when a substantial portion of net worth is tied to company equity.
4. Evaluate installment sales and transaction structure
Some business sales allow the seller to receive payments over multiple years rather than receiving the entire purchase price at closing.
When a transaction qualifies for the federal installment method, some gain may be recognized as payments are received rather than entirely in the year of sale.
This may affect the timing of federal and Colorado taxable income. However, not every transaction qualifies, and depreciation recapture and certain other income components may be recognized immediately.
An installment sale also introduces buyer credit risk, interest-rate considerations and uncertainty about future payments.
Before agreeing to payment terms, compare the after-tax economics of an installment sale with receiving the proceeds at closing and investing the funds independently.
5. Review tax-loss harvesting opportunities
Investors with unrealized losses in other investments may be able to realize those losses to offset capital gains, subject to federal and Colorado tax rules.
Tax-loss harvesting can be useful when selling a concentrated stock position, but the strategy should be evaluated across the entire portfolio.
Wash-sale rules, replacement investments, holding periods and the investor's long-term allocation should all be considered.
6. Coordinate the sale with retirement and estate planning
A major liquidity event can change a household's financial circumstances almost overnight.
Business owners and executives should consider what happens after the sale, including:
- How much of the proceeds should be reserved for federal and state taxes.
- How much should be invested in a diversified portfolio.
- Whether retirement can begin earlier than expected.
- How the proceeds affect future Roth conversions and required minimum distributions.
- Whether charitable giving or estate planning strategies should be coordinated with the transaction.
- How much liquidity should remain available for future purchases, taxes and spending.
The objective is to evaluate the liquidity event within the household's broader financial plan rather than treating the tax bill as the only consideration.
Investment management, retirement income, portfolio diversification and charitable planning become important decisions once the proceeds are available.
Explore Inclinevest services and fees →How Should Colorado Investors Prepare for a Large Liquidity Event in 2027?
Colorado's new graduated income tax structure creates another consideration for investors expecting significant taxable income in 2027.
For individuals with substantial stock gains, business-sale proceeds or equity compensation, the amount of Colorado taxable income recognized in a particular year may affect the applicable marginal state tax rate.
Consider an executive who expects $400,000 in ordinary Colorado taxable income and is evaluating whether to sell appreciated stock with a $700,000 gain.
If the entire gain is recognized in the same tax year, combined taxable income could reach approximately $1.1 million before other adjustments. A portion of that income could fall into the 8.4% marginal bracket under the 2027 structure.
This does not mean the investor should automatically sell in 2026. The decision should compare total federal and state tax consequences, transaction terms, market exposure and the investor's financial objectives.
A coordinated projection should examine:
- Expected federal adjusted gross income and Colorado taxable income.
- Short-term and long-term capital gains.
- Ordinary compensation and equity vesting.
- Federal capital gains rates and the net investment income tax.
- Colorado marginal income tax brackets.
- Charitable contributions and other available deductions.
- Potential installment payments or other transaction structures.
- Estimated tax payments and withholding requirements.
For some investors, recognizing income in a different year may be beneficial. For others, retaining the investment, diversifying gradually or completing the transaction sooner may produce a better overall financial outcome.
How Inclinevest Helps Investors Manage Wealth After a Liquidity Event
Completing a stock sale or business exit is only one part of a major financial transition. Once the proceeds arrive, investors need to decide how that capital fits into their broader financial picture.
Inclinevest Wealth Management provides ongoing investment management and financial planning for professionals, executives, business owners and retirees.
Depending on the client's circumstances, this may include:
- Investment management: Developing and managing a diversified portfolio based on the household's objectives, liquidity needs, risk tolerance and time horizon.
- Concentrated stock planning: Evaluating diversification strategies for appreciated investments and employer equity.
- Retirement planning: Evaluating when work becomes optional, how much can be spent and how investment assets can support future income.
- Tax-aware investment decisions: Considering asset location, tax-loss harvesting, charitable giving and the timing of portfolio withdrawals.
- Financial coordination: Working alongside the client's CPA and estate-planning attorney on financial decisions that involve multiple professionals.
Our firm operates on a fee-only basis. We do not receive commissions for selling investment products. Advisory fees are based on the assets managed and the applicable relationship terms. Flat annual planning fees may also be available depending on the scope and complexity of the engagement.
Client investment accounts are held with Charles Schwab & Co., Inc., an independent qualified custodian. Inclinevest provides investment advice and portfolio management while client assets remain in accounts maintained at Schwab.
We serve clients throughout Colorado and nationwide through a primarily virtual advisory relationship.
Learn more about our fee-only fiduciary approach and wealth management services and fees.
Frequently Asked Questions About Colorado Capital Gains Taxes
Does Colorado tax long-term capital gains?
Yes. Colorado generally includes taxable long-term capital gains in its income tax calculation. Although the federal government provides preferential rates for qualifying long-term gains, Colorado does not offer a general separate reduced capital gains rate.
Does Colorado tax stock sales differently from federal taxes?
Yes. Federal tax law generally distinguishes between short-term and long-term capital gains and provides preferential rates for qualifying long-term gains. Colorado generally includes taxable gains in its state income tax calculation without a comparable general preferential rate.
What is Colorado's capital gains tax rate in 2026?
Colorado's individual income tax rate for 2026 is 4.4%. Capital gains included in Colorado taxable income are generally subject to that rate, subject to applicable tax adjustments and other rules.
What is Colorado's capital gains tax rate in 2027?
Beginning in 2027, Amendment 87 establishes graduated marginal income tax rates of 3.7%, 4.2%, 4.4%, 7.4%, 7.9% and 8.4%, depending on taxable income. The applicable rate on an investment gain depends on the taxpayer's total taxable income.
Is there a Colorado capital gains tax exemption for selling stock?
Colorado does not generally provide a broad capital gains exemption for selling publicly traded stocks, ETFs, mutual funds or private-company shares. Its existing capital gain subtraction is primarily limited to qualifying agricultural real property gains for eligible taxpayers.
Does Colorado tax the sale of a privately held business?
Generally, yes. The tax treatment depends on whether the transaction is structured as an asset sale or stock sale, the type of business entity, the character of the income, the seller's residency and applicable federal and state tax rules.
Can I avoid Colorado capital gains taxes by moving to another state?
A genuine change of residency before a taxable transaction may affect Colorado's ability to tax certain investment gains. However, Colorado can continue to tax Colorado-source income received by nonresidents. Business interests, real estate, equity compensation and other income require separate sourcing analysis.
Does Colorado recognize the federal Section 1202 qualified small business stock exclusion?
Federal Section 1202 may provide an exclusion for qualifying small business stock. However, federal eligibility does not automatically establish identical Colorado treatment. The applicable Colorado additions, subtractions and statutory treatment should be reviewed with a qualified tax professional before a transaction.
Should I sell appreciated stock before Colorado's 2027 tax changes?
Not necessarily. The new marginal rates may increase state tax exposure for some higher-income households, but selling earlier can create other costs and risks. Compare the federal and Colorado tax consequences of both years, along with portfolio concentration, liquidity needs and investment objectives.
Can donating appreciated stock reduce capital gains taxes in Colorado?
Donating appreciated securities to an eligible charitable organization or donor-advised fund may avoid recognition of capital gains on the donated shares and may qualify for a federal charitable deduction, subject to applicable requirements. The contribution generally needs to occur before the sale becomes legally binding.
Work With a Fee-Only Fiduciary Wealth Advisor
A substantial stock sale or business exit can create financial opportunities, but it also introduces decisions that may affect taxes, investment risk, retirement timing and long-term wealth.
For Colorado investors, the new 2027 graduated income tax structure adds another variable to an already complex decision.
At Inclinevest Wealth Management, I work directly with professionals, executives, business owners and retirees to manage investments and coordinate financial planning around significant financial transitions.
As a fee-only fiduciary, I provide advice without receiving commissions from investment products. Client investments are custodied independently at Charles Schwab & Co., Inc.
If you are preparing to sell appreciated investments, exercise company stock options, participate in a private-company tender offer or exit a business, an introductory conversation is a good place to discuss your circumstances and determine whether an ongoing advisory relationship makes sense.
Planning for a Major Financial Transition?
Work directly with Gabriel Motta, CFP®, MBA, AWMA™, on investment management and financial planning following a significant stock sale, business exit or other liquidity event.
Inclinevest Wealth Management is an independent, fee-only fiduciary RIA serving clients throughout Colorado and nationwide.
Schedule an Introductory Consultation Learn about our services and fees →Additional Tax Resources
- Colorado General Assembly: Amendment 87 Ballot Analysis
- Colorado 2026 State Ballot Information Booklet
- Colorado Department of Revenue: Capital Gain Subtraction
- Colorado Department of Revenue: Part-Year Residents and Nonresidents
- IRS: Sale of a Business
- IRS: Stock Options
- Internal Revenue Code: Section 1202
This article is for informational and educational purposes only and is not individualized tax, legal or investment advice. Tax laws and administrative guidance may change. The examples are illustrative and do not represent actual client situations. Consult your CPA, tax attorney and financial adviser regarding your specific circumstances and before completing a significant financial transaction. Investment advisory services are offered through Inclinevest Wealth Management, a Colorado-registered investment adviser. Custody of client assets is provided by Charles Schwab & Co., Inc., Member SIPC.