
Financial Planning for Engineers and Technical Professionals
Engineers often have financial decisions that extend well beyond a salary and a retirement account. Equity compensation, employer stock, bonuses, complex benefit packages, tax planning, and career transitions can all affect how financial decisions fit together.
Inclinevest Wealth Management provides ongoing financial planning and investment management for engineers and technical professionals who want an integrated strategy for their income, investments, equity compensation, and retirement.
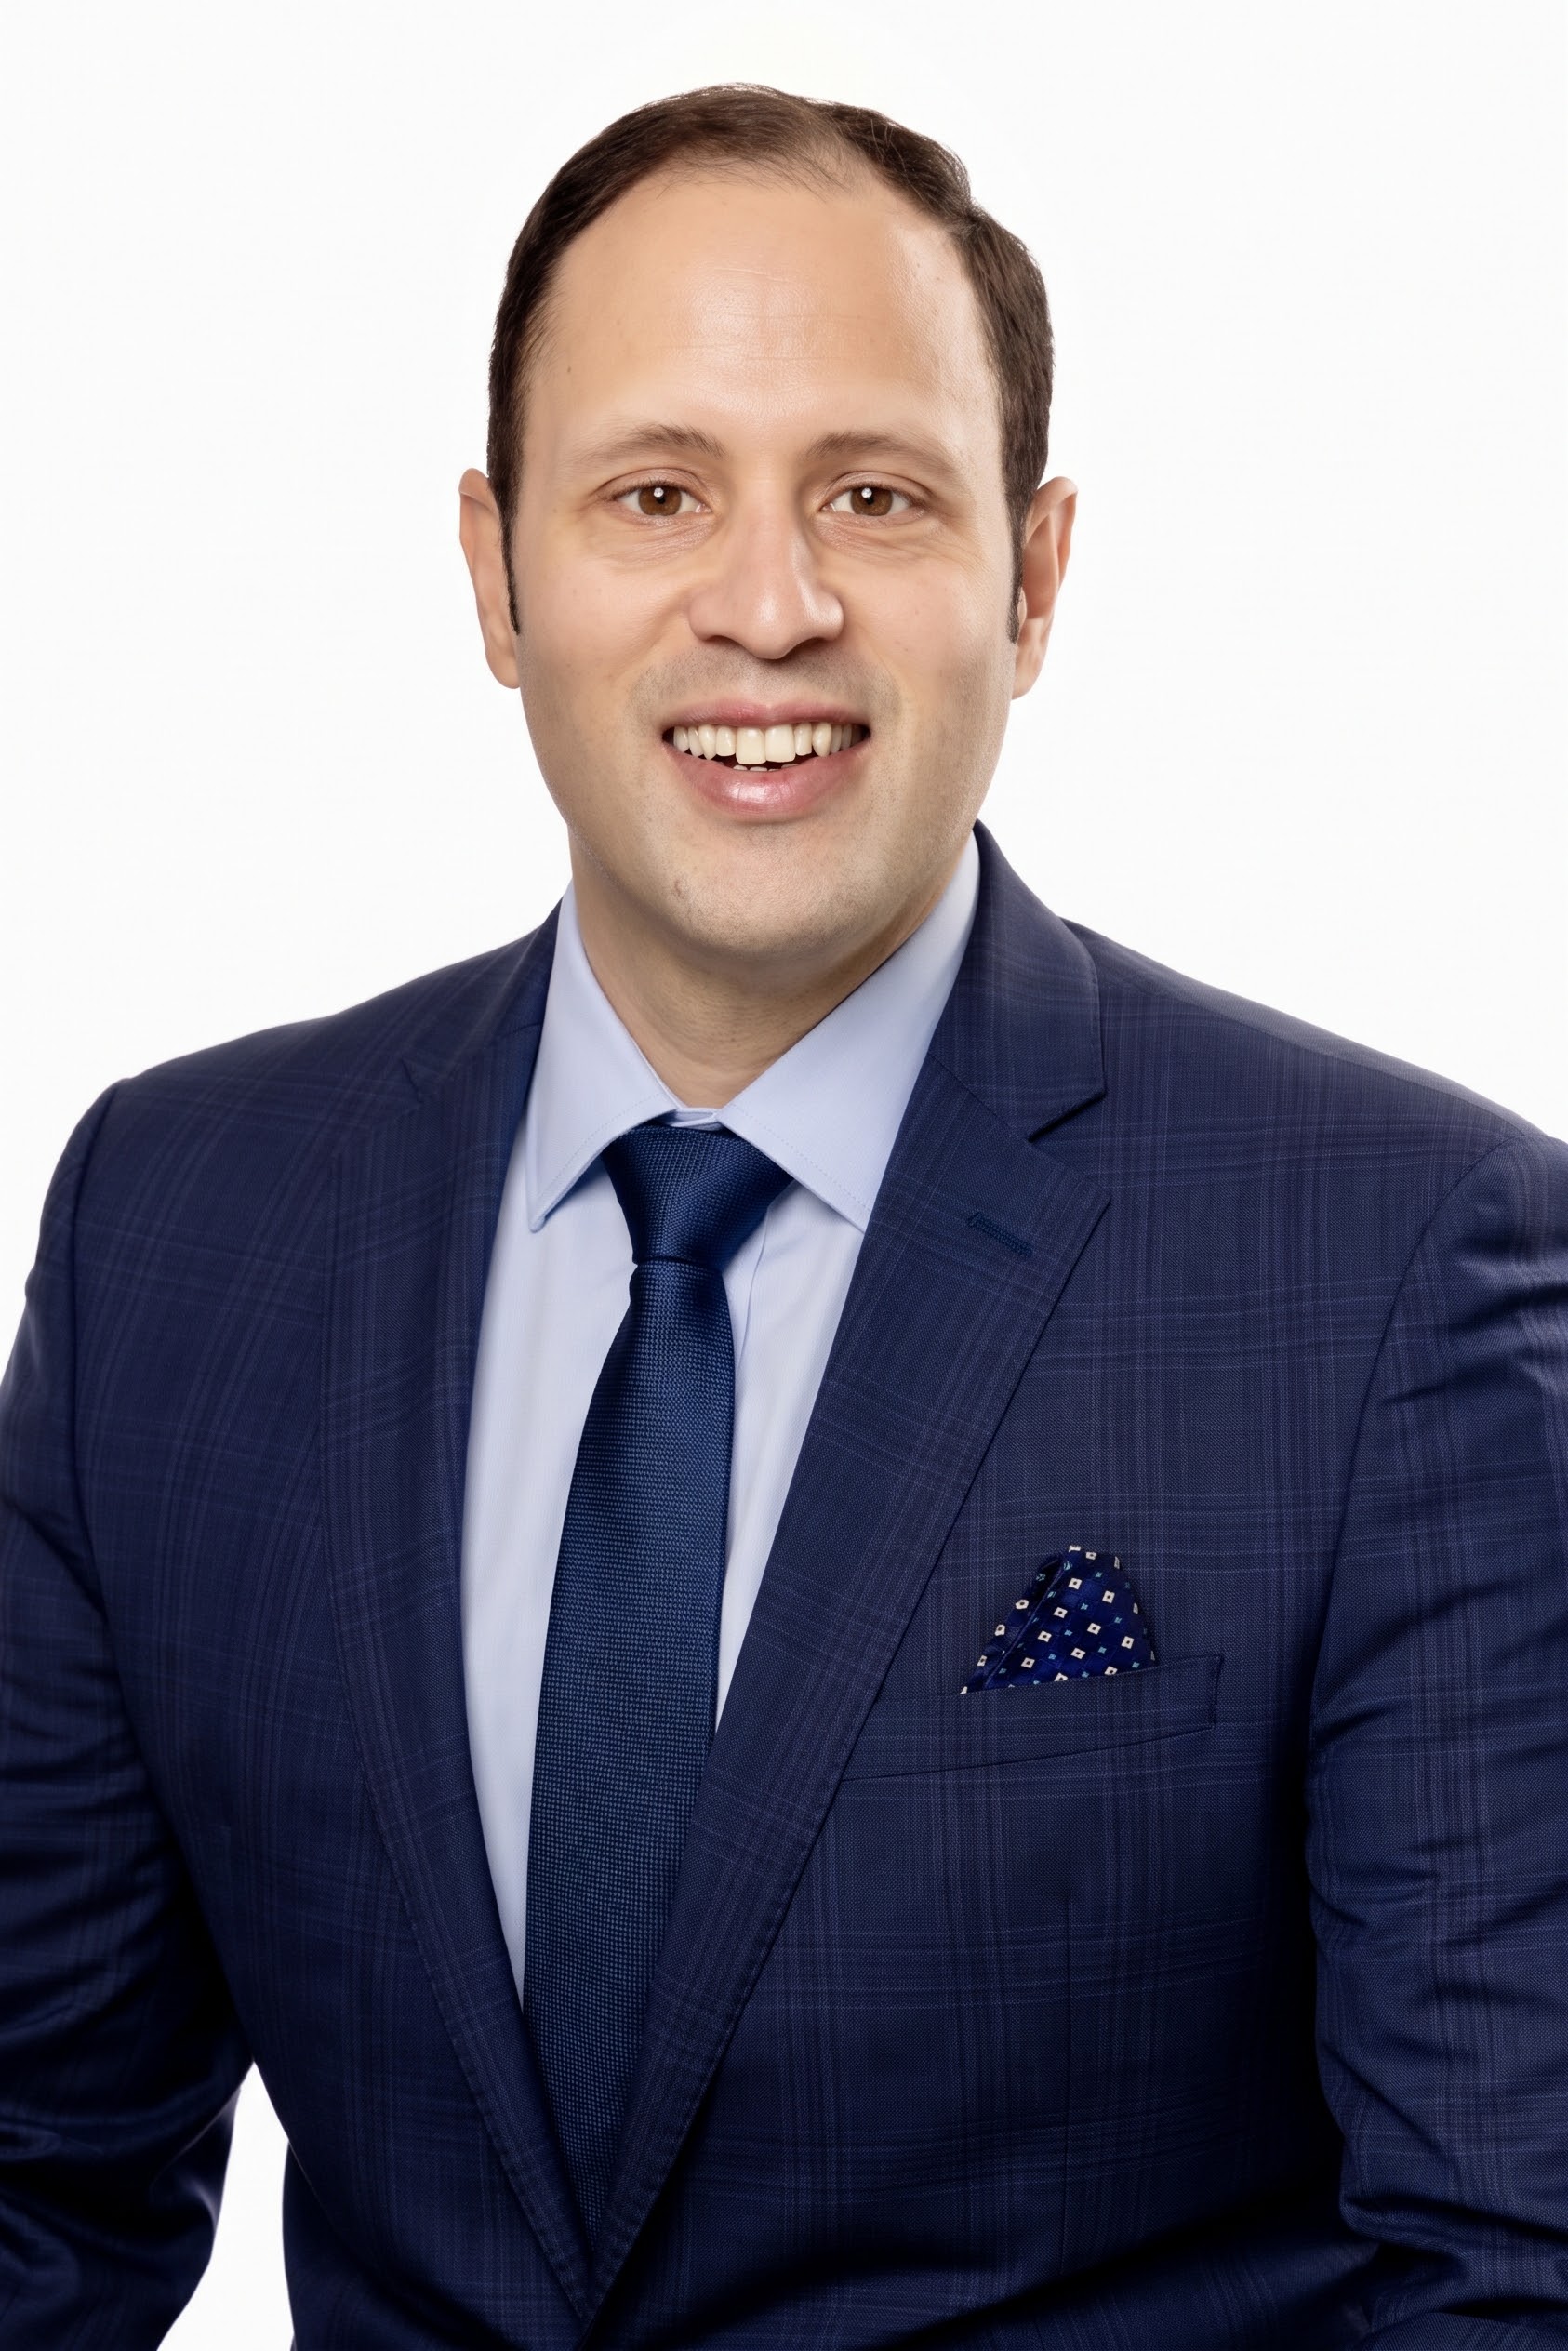
Founder & Wealth Advisor
Client investment assets are held at Charles Schwab & Co., Inc., in accounts in each client's name. Inclinevest provides independent financial planning and investment management, while Schwab serves as the qualified custodian.
Financial Planning for Engineers Requires More Than Investment Management
A strong income and a competitive benefits package can create significant financial opportunities, but they can also introduce decisions that are easy to overlook when each account or benefit is considered separately.
An engineer may have a traditional 401(k), an employee stock purchase plan, restricted stock units, stock options, an annual bonus, deferred compensation, and shares of an employer's stock. A government engineer may have a Thrift Savings Plan, a pension, and federal retirement benefits. Each has different rules, tax treatment, and planning considerations.
Inclinevest helps bring these decisions into one coordinated financial plan. Recommendations depend on your compensation, household finances, investment holdings, tax situation, career plans, and retirement timeline.
Salary, Bonuses and Benefits
Coordinate salary, annual incentives, deferred compensation, employer benefits, and savings decisions as income changes throughout your career.
Stock Options and Employer Shares
Evaluate RSUs, ISOs, NSOs, ESPPs, vesting schedules, exercise decisions, and the risks of holding too much company stock.
Portfolio and Tax Coordination
Coordinate workplace retirement accounts, taxable investments, IRAs, cash reserves, and tax-sensitive investment decisions.
Long-Term Retirement Strategy
Evaluate retirement timing, savings rates, pension benefits, Social Security, retirement-account withdrawals, and future income needs.
Who We Work With
Engineers work across industries, employers, and career stages. Financial planning should reflect the compensation structure and retirement benefits associated with the work, not assume every engineer has the same financial situation.
Aerospace, Defense and Space Professionals
Engineers and technical professionals working in aerospace, defense, aviation, space, and related technology fields may have complex retirement plans, employer stock, incentive compensation, and long careers with multiple employers.
Explore financial planning for aerospace and defense professionals.
Software and Technology Engineers
Software engineers, engineering managers, data professionals, and technology employees may receive RSUs, stock options, ESPP shares, bonuses, or other forms of equity compensation.
Manufacturing, Industrial and Energy Engineers
Professionals in manufacturing, industrial engineering, energy, infrastructure, and engineering consulting may need help coordinating employer retirement plans, bonuses, investment accounts, and changing compensation.
Government and Federal Engineers
Federal employees and government engineers may have a Thrift Savings Plan, FERS pension benefits, Social Security, and retirement decisions involving prior employer 401(k)s and IRAs.
Equity Compensation Planning for Engineers
Equity compensation can become a substantial part of an engineer's financial picture. Understanding when compensation is taxed, how shares are treated after vesting or exercise, and how much employer stock to retain can influence both investment risk and long-term financial flexibility.
Restricted Stock Units (RSUs)
RSUs generally become taxable compensation when they vest. Employers typically withhold taxes when shares are released, but withholding does not necessarily equal the employee's final tax liability. The shares retained after vesting become an investment holding, and a later sale generally creates a capital gain or loss measured against the applicable cost basis.
Planning may include reviewing vesting schedules, estimated tax payments, share-sale decisions, diversification, and how future vesting affects household income.
Incentive and Nonqualified Stock Options
Incentive stock options (ISOs) and nonqualified stock options (NSOs) have different tax rules. ISO exercises can create alternative minimum tax considerations, while NSO exercises generally create ordinary compensation income on the spread between the exercise price and fair market value.
Exercise decisions should account for the option expiration date, vesting schedule, available cash, concentration risk, tax exposure, and the possibility that the employer's stock price may decline.
Employee Stock Purchase Plans (ESPPs)
An ESPP may allow employees to purchase company shares at a discount. The tax treatment depends on the plan structure and holding period. Employees should understand the plan's purchase dates, discount, lookback provisions, trading restrictions, and the consequences of selling shares.
Concentrated Employer Stock
Engineers who receive stock through compensation or purchase shares through an employee plan can gradually accumulate a large position in one company. That can create a mismatch between employment income, career security, and investment risk.
A diversification strategy may consider vesting dates, tax lots, capital gains, charitable giving, trading windows, liquidity restrictions, and the role of employer stock in the broader portfolio.
Equity compensation should be considered alongside the rest of your financial plan.
The right decision for an individual stock award depends on the award type, employer plan, tax situation, liquidity needs, and investment portfolio. Inclinevest helps evaluate these decisions as part of a broader financial and investment strategy.
An engineer receiving annual RSU grants
Consider an engineer who receives RSUs each year in addition to salary and a cash bonus. When the RSUs vest, their value is generally included in taxable compensation. If the engineer keeps the shares, the portfolio may become increasingly tied to the same company that provides their employment income.
A financial plan can evaluate how much stock to retain, how to coordinate sales with other income and capital gains, and how to reinvest proceeds in a diversified portfolio. The appropriate strategy depends on the employee's circumstances and the applicable tax rules.
401(k), TSP and Employer Retirement Plan Decisions
Engineers may accumulate retirement assets across several employers over the course of a career. Understanding the available plans, investment options, fees, and distribution rules can help prevent unnecessary complexity and poor rollover decisions.
Making the Most of an Employer 401(k)
An employer retirement plan may include matching contributions, traditional and Roth contribution options, after-tax contributions, and an investment menu with varying costs and investment strategies.
Depending on the plan's rules, additional planning considerations may include:
- How much to contribute to receive the full employer match.
- Whether traditional or Roth contributions better fit the household's tax situation.
- Whether the plan permits after-tax contributions and in-service Roth conversions or distributions.
- How the plan's investment options and expenses compare with other retirement accounts.
- How the 401(k) fits alongside IRAs, taxable investments, and other workplace plans.
Should You Roll Over an Old 401(k)?
Changing employers can leave an engineer with retirement accounts at multiple institutions. A former employer's 401(k) may be left in the plan, transferred to a new employer's plan if accepted, or rolled over to an IRA.
A rollover should not be automatic. The decision may depend on investment choices, plan expenses, creditor protections, distribution flexibility, access to certain tax strategies, and whether the account contains pre-tax or after-tax assets.
Inclinevest can help evaluate how former employer retirement accounts fit into an overall investment and retirement strategy. Recommendations should account for the specific plan provisions and tax consequences before assets are moved.
Federal Engineers and the Thrift Savings Plan (TSP)
Federal engineers and other government employees may have retirement benefits that differ significantly from private-sector compensation packages. Depending on their employment history and eligibility, these may include the Federal Employees Retirement System (FERS), a TSP account, Social Security, and other federal benefits.
Retirement planning may involve coordinating the TSP with pension income, Social Security, IRAs, taxable investments, and retirement accounts from previous private-sector employers. It may also involve reviewing TSP withdrawal options, beneficiary designations, and whether a rollover is appropriate when leaving federal service.
A TSP rollover should be evaluated carefully. The TSP has its own investment options, costs, withdrawal provisions, and rules. Moving assets to an IRA is not automatically the best choice.
Financial planning for federal employees
For federal engineers and government employees, Inclinevest has a dedicated resource covering FERS, TSP accounts, federal retirement benefits, Social Security, and retirement income planning.
View financial planning for federal employees and TSP participants.
Tax Planning for Engineers and High-Income Professionals
Higher income, bonuses, equity compensation, and investment gains can create tax decisions that extend beyond annual tax filing. Planning ahead can help coordinate the timing and tax treatment of financial decisions.
Depending on the household's circumstances, planning considerations may include:
- Estimated tax payments and withholding related to bonuses and equity compensation.
- Capital gains and losses from selling employer stock or other investments.
- Tax implications of exercising incentive and nonqualified stock options.
- Traditional versus Roth retirement contributions.
- Roth conversions and the effect on current taxable income.
- Tax-efficient asset location across taxable, tax-deferred, and Roth accounts.
- Charitable giving strategies involving appreciated investments.
- Retirement withdrawal sequencing and future required minimum distributions.
Financial planning and tax preparation are different services. Inclinevest incorporates tax considerations into financial and investment recommendations and can coordinate with a client's tax professional. Inclinevest does not provide individual income tax return preparation.
Planning Around Career Changes and Financial Transitions
Engineers may change employers, move into management, accept a new compensation package, pursue consulting, or transition into retirement. Each change can affect income, benefits, equity awards, and retirement savings.
Changing Employers
Review unvested equity, stock option exercise windows, deferred compensation, health benefits, and retirement accounts before leaving an employer.
Relocation and Compensation Changes
Evaluate changes to salary, bonuses, benefits, housing costs, and tax circumstances when accepting a new role or relocating.
Consulting or Starting a Business
Plan for variable income, cash reserves, retirement contributions, insurance needs, and the transition from employee benefits to self-employment.
Approaching Retirement
Evaluate retirement timing, investment allocation, pension options, Social Security, healthcare costs, and how to convert accumulated assets into income.
Retirement Planning for Engineers
Retirement planning is about more than reaching a target account balance. It involves understanding how investments, retirement benefits, taxes, and future spending work together over time.
An engineer approaching retirement may have a 401(k), rollover IRA, Roth IRA, taxable investment portfolio, company stock, pension, or TSP. The plan should account for the different tax treatment, distribution rules, and timing considerations associated with each account.
How Much Do Engineers Need to Retire?
The amount required depends on expected retirement spending, other sources of income, investment assets, taxes, healthcare costs, inflation, and the age at which retirement begins. A retirement projection can help evaluate whether current savings and investment assumptions support the desired timeline.
Turning Retirement Savings Into Income
Retirement income planning may involve coordinating withdrawals from taxable accounts, traditional retirement accounts, Roth accounts, pensions, Social Security, and other sources. The sequence and timing of withdrawals can affect taxes and the long-term sustainability of a portfolio.
Retiring With Multiple Retirement Accounts
Engineers who have worked for several employers may have multiple 401(k)s, IRAs, or other retirement benefits. Consolidation may simplify management in some situations, but keeping accounts separate can also have advantages. The decision should be based on plan provisions, costs, investment choices, tax considerations, and the household's retirement strategy.
Learn more about retirement planning and how an integrated investment strategy can support retirement income.
What Should Engineers Look for in a Financial Advisor?
Engineers evaluating a financial advisor should look beyond investment performance claims or a list of financial products. The advisor's compensation, fiduciary responsibilities, planning process, and experience with the financial decisions relevant to the household are all important considerations.
| What to Evaluate | Questions to Ask |
|---|---|
| Fiduciary responsibility | Will the advisor act as a fiduciary when providing investment advice? |
| Compensation | How is the advisor paid? Are commissions or product incentives involved? |
| Equity compensation | Can the advisor help evaluate RSUs, stock options, ESPPs, and concentrated employer stock? |
| Retirement planning | Can the advisor coordinate 401(k)s, IRAs, TSP accounts, pensions, and retirement income? |
| Tax coordination | Does the financial plan consider the tax consequences of investment and retirement decisions? |
| Ongoing advice | Will the advisor review the plan as compensation, investments, family circumstances, and goals change? |
Inclinevest is a fee-only fiduciary registered investment adviser. The firm does not earn commissions from selling investment products. Advisory fees and the scope of services are explained before an advisory relationship begins.
Read more about why fee-only financial advice matters and Inclinevest's investment philosophy.
How Inclinevest Works With Engineers
Inclinevest works with individuals and families seeking an ongoing financial planning and investment management relationship. The first conversation is an opportunity to discuss your financial situation, the decisions you are facing, and whether the firm's services are a good fit.
Introductory Conversation
Discuss your financial situation, career and compensation, investment accounts, retirement goals, and what you are looking for in a financial advisor.
Review and Planning
If there is a mutual fit, review the relevant financial information and develop recommendations based on your goals, circumstances, and planning priorities.
Ongoing Advice
Continue with an ongoing advisory relationship that incorporates investment management and financial planning as your circumstances change.
Fee-Only Fiduciary Advice
Inclinevest is compensated by advisory fees rather than commissions from investment product sales. Fees depend on the services provided and the scope of the advisory relationship.
Frequently Asked Questions About Financial Planning for Engineers
Do engineers need a financial advisor?
An engineer may benefit from a financial advisor when compensation, investments, employer benefits, and retirement accounts create financial decisions that need to be coordinated. This can include equity compensation, employer stock, 401(k) contributions, tax planning, career changes, and retirement income. The need for an advisor depends on the complexity of the household's finances and the level of ongoing advice desired.
What does a financial planner for engineers help with?
Financial planning for engineers can include investment management, equity compensation, stock options, RSUs, ESPPs, employer retirement plans, 401(k) rollovers, tax-sensitive investment decisions, insurance considerations, and retirement planning. The recommendations should reflect the engineer's compensation structure, career plans, and household financial goals.
Can a financial advisor help with RSUs and stock options?
A financial advisor familiar with equity compensation can help evaluate vesting schedules, exercise decisions, tax considerations, employer stock concentration, and diversification strategies. RSUs, ISOs, and NSOs have different tax rules, so the specific award type and plan documents matter.
Should I sell company stock when my RSUs vest?
The decision depends on your investment concentration, tax situation, financial goals, trading restrictions, and confidence in the company's future. Because RSUs are generally taxed as compensation when they vest, holding the shares after vesting is an investment decision that can increase exposure to one company. A diversification strategy should consider the rest of your portfolio and your employment income.
Should I roll over my old employer's 401(k) into an IRA?
Not necessarily. You may be able to leave the assets in the former employer's plan, transfer them to a new employer's plan, or roll them into an IRA. Compare investment options, expenses, creditor protections, distribution flexibility, and tax considerations before deciding. The best choice depends on the specific plans and your financial situation.
Can Inclinevest help engineers with a TSP and federal retirement benefits?
Inclinevest provides financial planning for federal employees, including planning considerations involving the Thrift Savings Plan, FERS pension benefits, Social Security, and other retirement assets. The firm can help evaluate how these benefits fit into an overall retirement strategy, including decisions involving prior employer 401(k)s and IRAs.
Can engineers use a mega backdoor Roth strategy?
Some employer retirement plans permit after-tax 401(k) contributions followed by an in-service Roth conversion or distribution. This strategy is commonly called a mega backdoor Roth. Availability depends on the plan's specific provisions, contribution limits, and distribution rules. It is not available through every employer plan.
How should engineers plan for retirement?
Retirement planning should consider expected spending, retirement timing, investment assets, 401(k)s, IRAs, pensions, TSP accounts, Social Security, taxes, and healthcare costs. Engineers with equity compensation or multiple employer retirement accounts may also need to evaluate stock diversification and the timing of retirement-account withdrawals.
Is Inclinevest a fee-only fiduciary financial advisor?
Yes. Inclinevest Wealth Management is a fee-only fiduciary registered investment adviser. The firm is compensated through advisory fees rather than commissions from the sale of investment products. The firm's services and fees are discussed before an advisory relationship begins.
Does Inclinevest prepare tax returns?
No. Inclinevest incorporates tax considerations into financial planning and investment recommendations but does not provide individual income tax return preparation. The firm can coordinate with a client's CPA or other tax professional when appropriate.
Does Inclinevest work with engineers outside Colorado?
Inclinevest works with clients across the United States through virtual meetings, subject to applicable state registration requirements. An introductory conversation can establish whether the firm can work with you based on your state of residence and financial planning needs.
Looking for a Financial Advisor Who Understands Your Financial Picture?
Whether you are managing equity compensation, evaluating retirement benefits, changing employers, or preparing for retirement, Inclinevest can help coordinate your investments and financial decisions through an ongoing planning relationship.
Schedule an Introductory CallLearn more about Inclinevest Wealth Management or review services and fees.
Inclinevest provides independent investment advice. Client assets are held at Charles Schwab & Co., Inc., in accounts in the client's name. Schwab provides custody and related brokerage services; it does not sponsor, endorse, or supervise Inclinevest.
Inclinevest Wealth Management is a registered investment adviser. Advisory services are offered only in jurisdictions where the firm is appropriately registered or exempt from registration. Information on this page is for general educational purposes and should not be considered individualized investment, tax, or legal advice. Investing involves risk, including the possible loss of principal. Tax treatment depends on individual circumstances and applicable law.