
Fee-Only Fiduciary Wealth Management
Financial Advisor for High-Income Professionals
Financial planning and investment management for established professionals, executives, and business owners building and managing significant wealth.
We bring investments, taxes, equity compensation, retirement income, and family wealth together through an ongoing financial plan. Our work is designed around your financial situation, priorities, and long-term goals.
Fee-only fiduciary advice · CFP® professionals · Ongoing investment management
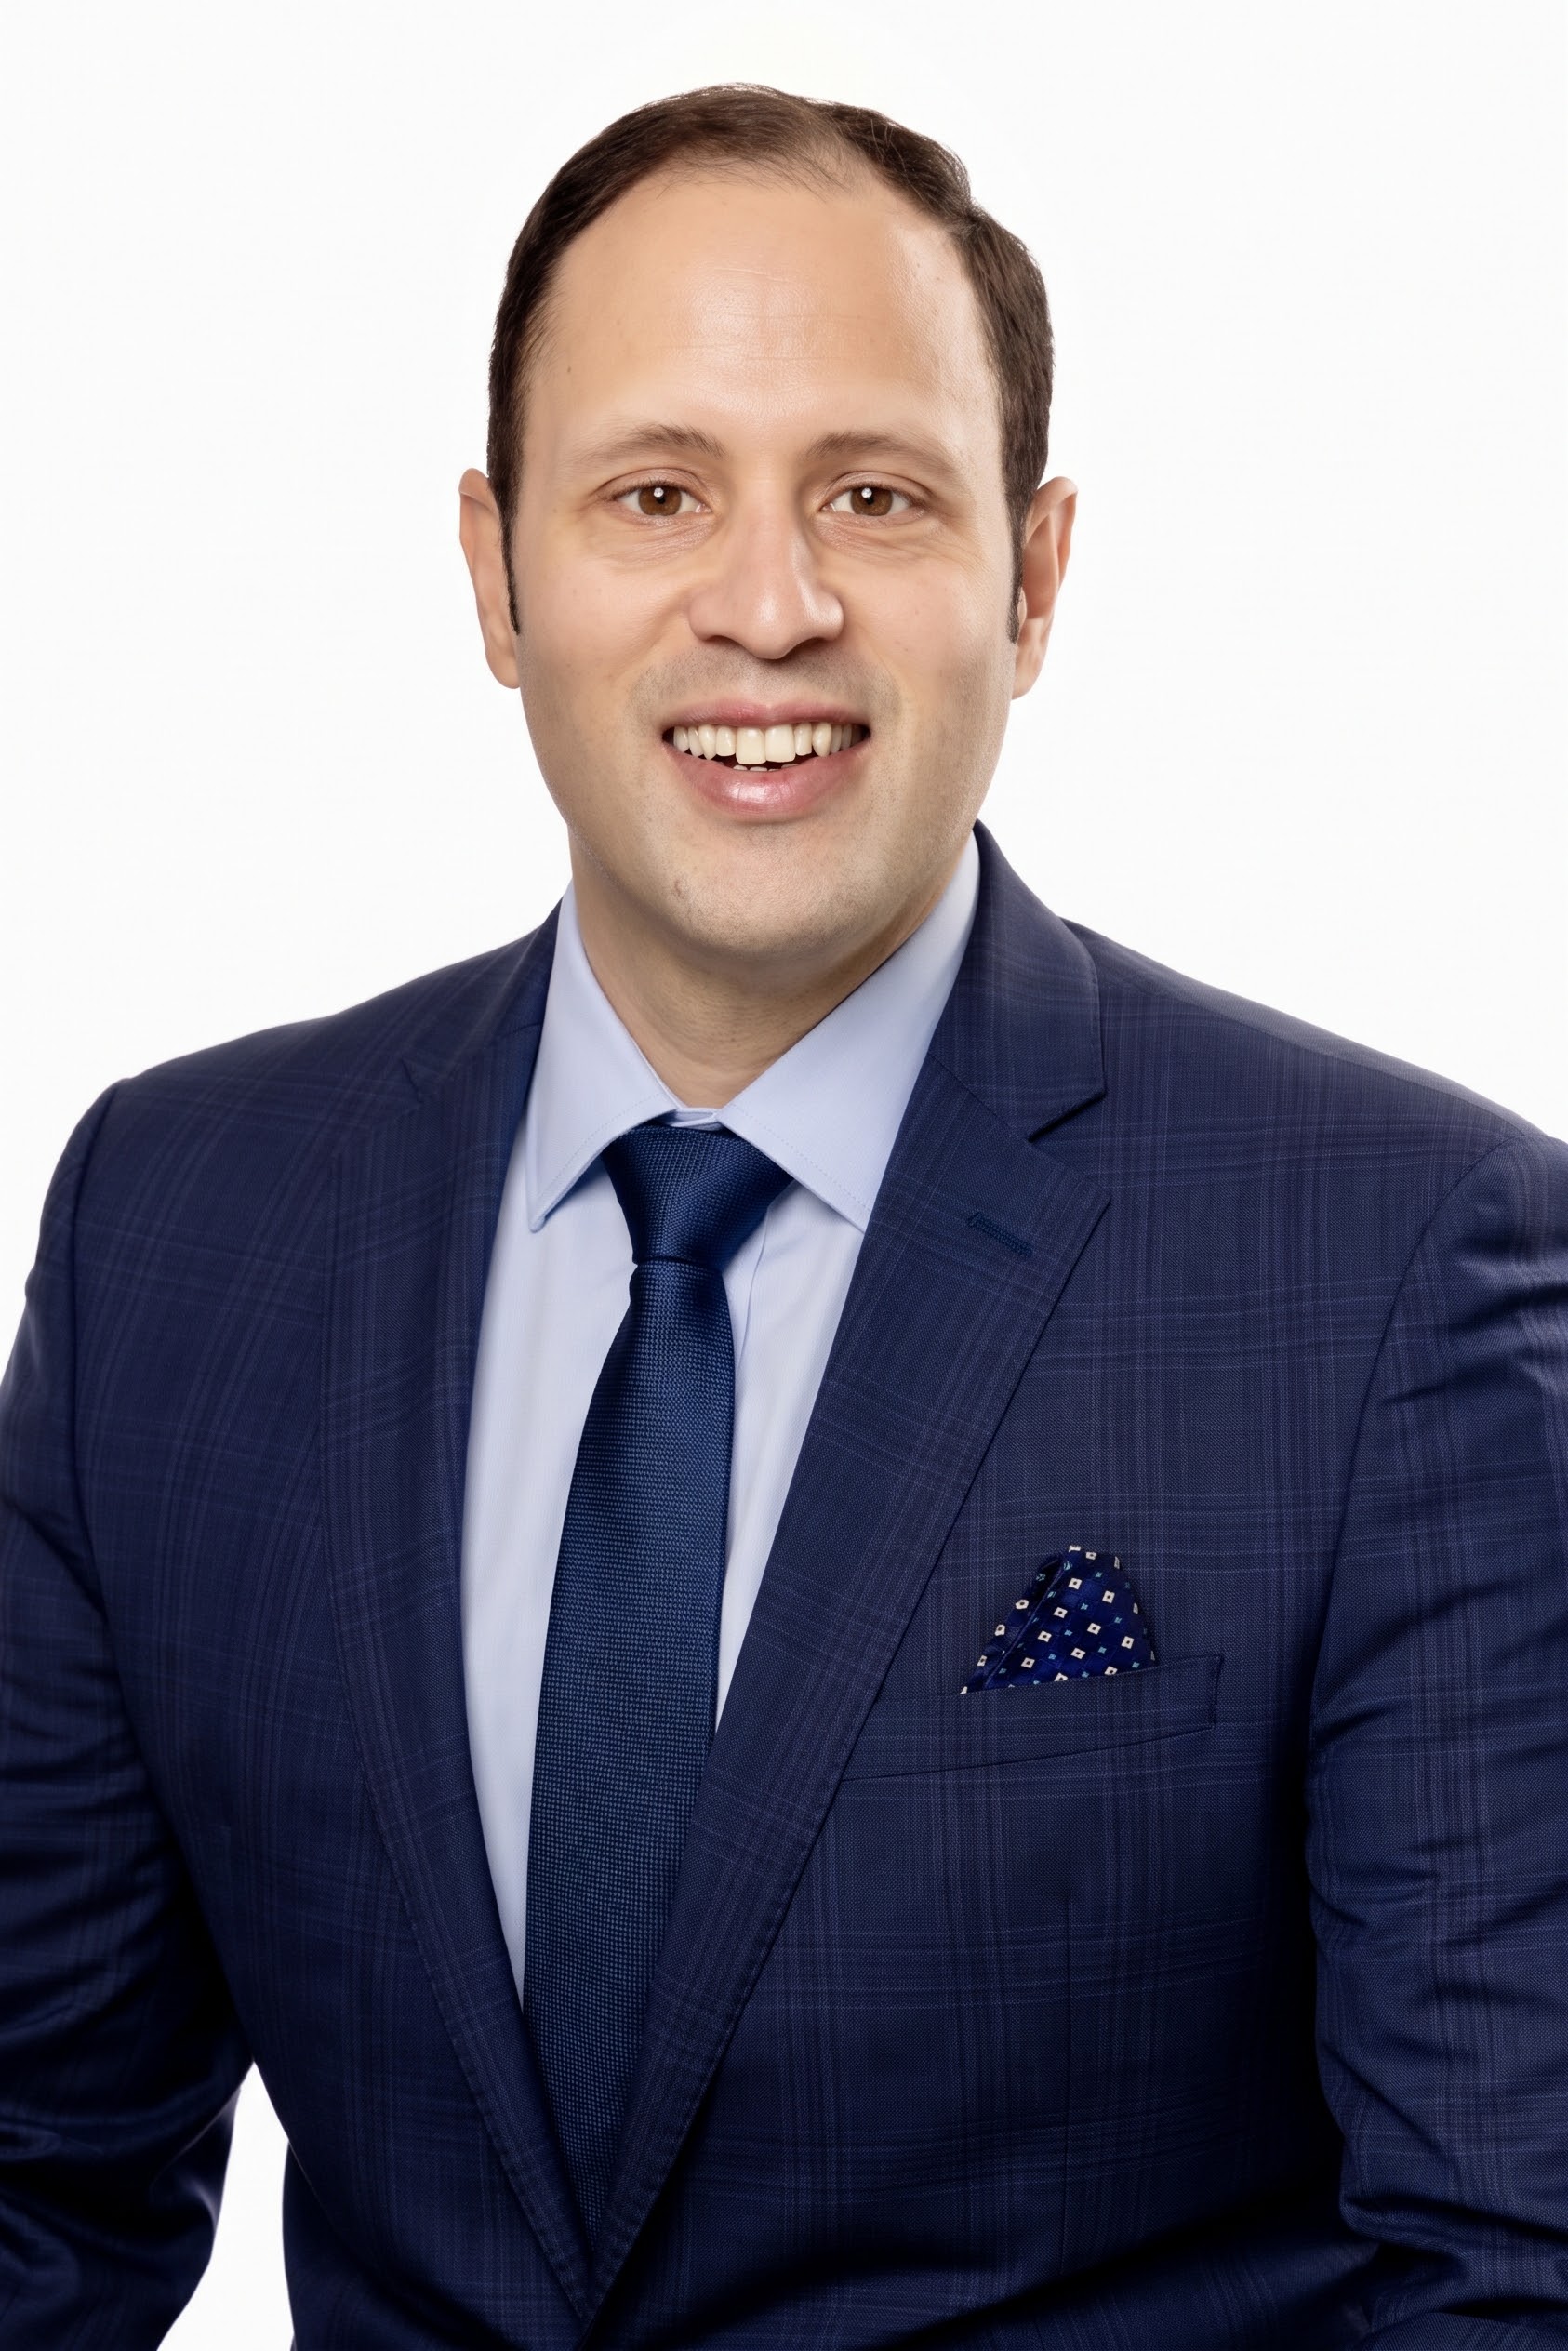
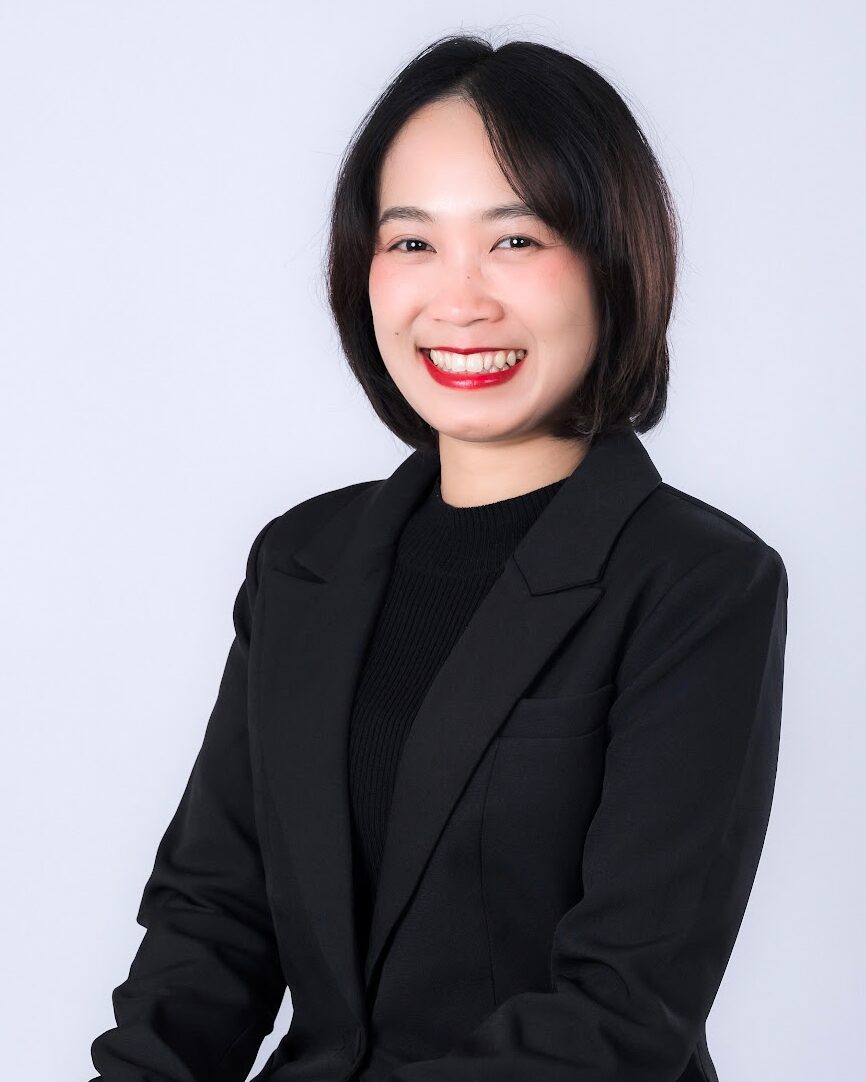
Gabriel Motta, CFP®, MBA, AWMA™ & Sunisa Motta, CFP®, EA
Colorado-Based Financial Planning. Serving Clients Nationwide.
Inclinevest Wealth Management is an independent, fee-only fiduciary registered investment adviser based in Colorado. We provide ongoing financial planning and investment management for professionals, executives, business owners, and families throughout the United States.
 Client investment assets held at Charles Schwab, an independent qualified custodian
Financial Planning for High Earners
When Your Income and Wealth Grow, Financial Decisions Become More Connected
A successful career can bring substantial income, retirement savings, equity compensation, taxable investments, real estate, and business interests. Each may have its own tax treatment, investment considerations, and financial decisions.
Managing these pieces separately can make it harder to understand how they affect one another. A retirement contribution can influence your current tax situation. Employer stock can create concentration risk. A business sale or inheritance can change your investment strategy and retirement timeline.
A financial advisor for high-income professionals helps coordinate investments, taxes, retirement planning, equity compensation, cash flow, and long-term wealth decisions. Inclinevest brings these areas together through ongoing financial planning and investment management, with recommendations based on your circumstances rather than generic rules.
Inclinevest Wealth Management works with established professionals and families who want an ongoing advisory relationship as they build wealth, approach retirement, manage inherited assets, and plan for the next generation.
Who We Work With
Financial Planning for Professionals With Complex Financial Lives
We work with professionals whose compensation, investments, and financial responsibilities have become more complex as their careers and assets have grown.
Physicians
Coordinate retirement accounts, investments, taxes, retirement income, and major career or practice decisions.
Financial planning for physicians →Dentists
Plan around practice ownership, retirement savings, practice transitions, investment management, and retirement income.
Financial planning for dentists →Engineers
Coordinate employer benefits, equity compensation, retirement plans, concentrated stock, and long-term investment decisions.
Financial planning for engineers →Technology Professionals
Plan around high salaries, bonuses, RSUs, stock options, concentrated company stock, and changing compensation.
Equity compensation planning →Executives
Coordinate executive compensation, equity awards, deferred compensation, investments, taxes, and retirement planning.
Executive compensation planning →Aerospace and Defense Professionals
Plan around retirement benefits, equity compensation, bonuses, employer stock, career changes, and retirement income.
Aerospace and defense planning →Business Owners
Connect business interests, personal investments, retirement planning, cash flow, and the financial impact of a future sale.
Planning after selling a business →Other Established Professionals
Engineers, attorneys, consultants, senior managers, and other professionals with substantial income and growing investment assets.
Explore professional financial planning →Pre-Retirees and Retirees
Evaluate retirement timing, investment risk, portfolio withdrawals, taxes, Social Security, and sustainable retirement income.
Retirement financial planning →Comprehensive Financial Planning
What Does Financial Planning for High-Income Professionals Include?
The right strategy depends on your income, investments, tax situation, risk tolerance, time horizon, cash flow needs, and family priorities. These are some of the areas we address through ongoing planning and investment management.
Retirement Planning and Income
Planning for Retirement 5 to 15 Years Before You Leave Your Career
For many established professionals, the years leading up to retirement are when investment balances are substantial, earnings are near their peak, and financial decisions have lasting consequences. Planning ahead can help connect your retirement date, portfolio, taxes, and future income.
Build the Retirement Strategy
Estimate future spending, evaluate savings rates, coordinate pre-tax, Roth, and taxable accounts, and assess the role of employer stock and other concentrated investments.
Prepare for the Transition
Evaluate portfolio risk, potential Roth conversions, Social Security timing, retirement dates, and how to prepare financially for leaving your career.
Develop the Income Plan
Coordinate withdrawal sequencing, health coverage before Medicare, required distributions, taxes, and how your investments will support retirement spending.
Retirement Is Also an Investment and Income Decision
Accumulating assets and relying on those assets for income require different planning considerations. We evaluate how your portfolio, Social Security, retirement accounts, taxes, and spending needs work together before and after retirement.
Explore retirement financial planning | Learn about retirement income planning
Equity Compensation and Employer Stock
Planning Around RSUs, Stock Options, and Concentrated Investments
Equity compensation can become a substantial part of your financial picture. Restricted stock units, stock options, employee stock purchase plans, and employer shares can create opportunities while also increasing investment concentration and tax complexity.
For example, withholding at vesting may not cover the full tax liability on RSUs. Exercising incentive stock options can create alternative minimum tax considerations. Selling appreciated shares can trigger capital gains, while holding too much employer stock can increase the financial risk tied to one company.
We evaluate these decisions in the context of your overall portfolio, cash flow, tax situation, retirement goals, and other assets.
Equity compensation planning may include
- Restricted stock units and vesting schedules
- Nonqualified stock options
- Incentive stock options
- Employee stock purchase plans
- Exercise and diversification decisions
- Concentrated employer stock
- Capital gains and tax exposure
- Integration with retirement and investment goals
Tax-Aware Financial Planning
Tax Planning for High-Income Professionals
Tax decisions affect more than the current year's tax bill. Retirement contributions, investment gains, equity compensation, charitable giving, and the timing of retirement income can influence your financial picture over many years.
Retirement Contributions
Evaluate traditional and Roth contributions in light of current income, expected future tax rates, and retirement goals.
Roth Conversions
Evaluate whether converting pre-tax retirement assets to Roth accounts makes sense based on projected income, tax rates, and the broader plan.
Investment Taxes
Coordinate asset location, capital gains, tax-loss harvesting, and withdrawals with the overall investment strategy.
Charitable Giving
Consider tax-aware charitable strategies, including donations of appreciated securities when appropriate.
Equity Compensation
Understand the financial and tax considerations of vesting, exercising, selling, and holding employer equity.
Required Minimum Distributions
Plan for required distributions and their potential effect on taxable income, Medicare premiums, and retirement cash flow.
We coordinate with your CPA and other tax professionals when appropriate. Inclinevest provides financial planning and investment management, not tax preparation or legal services.
Investment Strategy
Investment Management Built Around Your Financial Plan
Your investment portfolio should reflect more than your age or a generic risk questionnaire. We consider your financial situation, retirement timeline, spending needs, other assets, tax circumstances, and ability to tolerate investment losses.
Our approach emphasizes diversification, investment costs, tax considerations, and evidence-based portfolio management. We select investments based on their role in the overall portfolio rather than a proprietary product lineup.
What we consider
- Asset allocation and diversification
- Taxable and tax-advantaged accounts
- Employer stock and concentrated positions
- Risk tolerance and risk capacity
- Retirement time horizon
- Cash reserves and liquidity needs
- Investment fees and expenses
- Other assets and sources of income
Wealth Transitions and Family Wealth
Planning for Inheritance, Business Sales, and the Next Generation
As wealth grows, financial planning can extend beyond saving and investing. Inheritance, business sales, trust distributions, family support, and charitable goals can introduce new decisions about how assets are managed and eventually transferred.
Inheritance and Sudden Wealth
Evaluate inherited investments, inherited retirement accounts, trust distributions, and other significant changes in wealth.
Inheritance and sudden wealth planning →Business Sales and Liquidity Events
Plan for the investment, tax, cash flow, and retirement considerations that follow a business sale or other major financial event.
Financial planning after selling a business →Trust and Beneficiary Planning
Incorporate trust assets, beneficiary interests, distributions, and investment decisions into a broader financial plan.
Financial planning for trust beneficiaries →Multigenerational Wealth
Consider how investments, gifting, charitable giving, and family wealth may support the people you care about and future generations.
Learn about trust planning considerations →Planning for More Than Your Own Retirement
Your financial plan may need to account for children, other family members, charitable priorities, and the eventual transfer of wealth. We incorporate investment and financial planning considerations into an ongoing relationship and coordinate with your estate planning attorney and tax professional where appropriate.
Independent Fiduciary Advice
Why Work With a Fee-Only Fiduciary Financial Advisor?
Financial professionals can have different compensation arrangements and responsibilities. Inclinevest is an independent, fee-only fiduciary firm focused on ongoing financial planning and investment management.
Fee-Only Compensation
Our compensation comes directly from advisory clients. We do not receive commissions for recommending financial products.
Why fee-only matters →Fiduciary Responsibility
When providing investment advice, we are subject to a fiduciary duty to act in the best interests of our advisory clients.
Learn about fiduciary advice →CFP® Professionals
Financial planning and investment management are provided by Gabriel Motta, CFP®, MBA, AWMA™, and Sunisa Motta, CFP®, EA.
Meet the advisors →Ongoing Financial Planning
Investment management and financial planning continue as income, investments, goals, and circumstances change.
Independent Custody
Client investment assets are held at Charles Schwab, an independent qualified custodian. Schwab provides custody and account services.
Colorado-Based, Nationwide Service
Inclinevest is based in Colorado and works with clients throughout the United States.
Learn more about the firm, our investment approach, and the advisory relationship on our About Inclinevest and Services & Fees pages.
Ongoing Advisory Relationship
How the Financial Planning Relationship Works
We begin by understanding your financial situation, identifying the decisions that matter most, and developing a coordinated plan. Investment management and financial planning continue as an ongoing relationship.
Understand Your Finances
Review income, investments, retirement accounts, taxes, equity compensation, spending, and other relevant financial information.
Identify the Decisions
Determine which financial decisions deserve attention now and which can be addressed over time.
Develop Your Strategy
Evaluate your situation and develop recommendations for investments, taxes, retirement, cash flow, and other priorities.
Implement the Plan
Put recommendations into action and coordinate with your tax, legal, and other professional advisors when appropriate.
Manage Your Investments
Manage your portfolio in accordance with your investment strategy and financial objectives.
Continue Planning
Revisit your financial plan as your income, investments, family, goals, and circumstances change.
Inclinevest focuses on ongoing financial planning and investment management relationships. We generally do not provide hourly consultations or standalone financial plans.
Colorado and Nationwide
Based in Colorado. Serving Clients Nationwide.
Inclinevest Wealth Management is based in Colorado and serves professionals, executives, business owners, and families throughout the Denver metro area, across Colorado, and nationwide.
Our financial planning and investment management relationships are built around your financial situation, assets, goals, and priorities, regardless of where you live.
We can also coordinate financial planning with your CPA, estate planning attorney, and other professional advisors when appropriate.
Discuss Your Financial Situation
Bring Your Financial Decisions Together
If your income, investments, equity compensation, taxes, or retirement planning have become more complex, an introductory conversation can help determine whether Inclinevest is a good fit.
Common Questions
Financial Advisor for High-Income Professionals FAQ
What does a financial advisor for high-income professionals do?
A financial advisor for high-income professionals helps coordinate investments, taxes, retirement planning, equity compensation, cash flow, and other financial decisions as income and wealth grow. The goal is to bring these areas together rather than evaluate each account or decision separately.
What types of professionals does Inclinevest work with?
Inclinevest works with physicians, dentists, engineers, technology professionals, executives, aerospace and defense professionals, business owners, and other established professionals and families.
Explore our pages for physicians, dentists, and engineers.
How much income or investment assets do I need to work with Inclinevest?
We typically work with clients who have $1 million or more in investable assets and want ongoing financial planning and investment management. The appropriate advisory relationship depends on the assets involved, planning needs, and scope of services.
If you are unsure whether your situation is a fit, you can schedule an introductory conversation.
Can you help with equity compensation and concentrated stock?
Yes. Financial planning can include RSUs, stock options, employee stock purchase plans, vesting schedules, employer stock concentration, diversification, and related tax considerations. We evaluate these decisions alongside your broader investment portfolio and financial goals.
Learn more about equity compensation financial planning.
Can you help coordinate tax planning for high earners?
We incorporate tax considerations into financial planning and investment management. This can include retirement contributions, Roth conversions, capital gains, tax-loss harvesting, equity compensation, charitable giving, and retirement withdrawals. We coordinate with your CPA when appropriate. Inclinevest does not prepare tax returns or provide tax or legal services.
Do you help professionals plan for retirement income?
Yes. Retirement planning can include evaluating when you can retire, estimating spending needs, coordinating Social Security, managing retirement accounts, evaluating withdrawal strategies, and developing a plan for how your investments can support retirement income.
See our retirement planning and retirement income planning pages.
Can you help with inheritance and multigenerational wealth planning?
Yes. Financial planning can incorporate inherited investments, inherited retirement accounts, trust distributions, charitable giving, family support, and investment decisions involving multiple generations. We can coordinate with your estate planning attorney and tax professional on legal and tax matters.
Learn more about inheritance and sudden wealth planning.
How does Inclinevest charge for financial planning and investment management?
Inclinevest is fee-only and is compensated directly by advisory clients. Fees are based on the advisory relationship and assets under management. We do not receive commissions for recommending financial products.
Review the current fee schedule and service details on our Services & Fees page.
Do you work with clients outside Colorado?
Yes. Inclinevest is based in Colorado and serves clients throughout the United States through ongoing financial planning and investment management relationships.
Where are client investments held?
Client investment assets are held at Charles Schwab, an independent qualified custodian. Schwab provides custody and account services, while Inclinevest provides financial planning and investment management.
Does Inclinevest provide one-time financial plans or hourly advice?
Inclinevest focuses on ongoing investment management and financial planning relationships. We generally do not provide hourly consultations or standalone financial plans.
Inclinevest Wealth Management
Let's Discuss Your Financial Plan
If you are managing substantial income, investments, equity compensation, or retirement assets, we can discuss your financial situation, the decisions ahead, and whether an ongoing advisory relationship is appropriate.
Colorado-based fee-only fiduciary financial advisor · Serving clients nationwide · Investments held at Charles Schwab